Den här sidan finns ännu inte på svenska. Vi jobbar på det. Tills vidare är den tillgänglig på engelska.

This content is available in English language only

10 Years of Ethereum: Evolution, Architecture & Adoption in 10 Charts

10 Years of Ethereum: Evolution, Architecture & Adoption in 10 Charts| Bitwise
  • Ethereum’s greatest strength is its ability to adapt without losing coherence, evolving through cultural forks, architectural pivots, and economic redesigns that most platforms wouldn’t survive.
  • Ethereum’s architecture and economic model has pivoted a few major times to combine network adoption and value capture, and improve validator and user experience.
  • With regulatory clarity, stablecoin rails, DeFi dominance, RWA applications and ETF flows converging, Ethereum isn’t chasing the next narrative—it’s aiming to become the institutional foundation that underwrites it.

1. Genesis: Programmable Money Emerges (2015)

In October 2013, Vitalik Buterin visited the Mastercoin team in Israel. When his proposed upgrades were rejected, he branched off to design Ethereum (coincidentally, just a few blocks from where Bitwise was later founded in 2017, in San Francisco).

Co-founders Gavin Wood and Charles Hoskinson (now of Polkadot and Cardano) joined Buterin, along with Jeff Wilcke, to define Ethereum's base-layer primitives: a virtual machine to execute smart contracts, gas limits to meter compute, and a consensus protocol to validate blocks.

Ethereum launched on July 30, 2015, with around 30 contributors and a roadmap including four core upgrades: Frontier (basic mining), Homestead (network reliability), Metropolis (user interfaces), and Serenity (Proof of Stake, later named The Merge).

During each phase, Ethereum laid the foundations of its mission to becoming a decentralized, global financial operating system.

Order of launches Chart 1
Source: Bitwise Europe, as of 23rd July 2025; NB: list of tokens may not be exhaustive

2. The DAO Hack: Resilience Through Forks (2016)

Ethereum's founding idea was clear: a decentralized, rules-based, global financial platform where software enforced trust, not institutions. The first large-scale application was “The DAO”, an experimental, community-run investment fund that raised $150m in ETH and aimed to invest in projects in the Ethereum space. A future was promised where capital allocation was governed by code, not corporations.

This trust was broken nine months post-launch. A vulnerability in The DAOs smart contract allowed an attacker to siphon $70M, worth 3.6M ETH.

Ethereum faced its first existential dilemma: should the community stick to the principle of “code is law”, or does it intervene to protect users and their assets.

A soft fork was proposed-a gentle upgrade that would freeze the stolen funds by blacklisting the hacker's address. In a soft fork, the network stays on the same chain, but different rules are introduced that older computers can still follow. Think of it like changing the rules of a football game without kicking anyone off the field.

But the attacker responded with a public bribe: promising to reward miners with the stolen funds who ignored the fork. That threat was enough to divide the community. Many miners and users chose to abandon the original chain and follow a new one that reversed the hack, much to the hackers' enjoyment.

This kind of split is called a hard fork-when the network breaks into two chains that no longer follow the same rules or history, and the computers on either chain cannot understand each other. Think of it like the original football game splitting into two, with the second football game implementing different rules the players of the first game don't understand.

At this point in time, there was a divergence in philosophy in the ecosystem, which caused the split. As a result, Ethereum Classic (ETC) was born. This community took the view that immutability rules. That trust in the system means accepting outcomes, even painful ones. ETC stood for purity of principle, but lost developer momentum, adoption and capital in the years to come.

Ethereum, however, chose social consensus over “code is law”, prioritising restoring stolen funds, preserving investor confidence and affirming that Ethereum was a community with agency. This foreshadowed Ethereum's attitude almost 10years later.

At first, investors and the community were unsure. ETC began trading in wide ranges between $0.84-$1.62, reflecting initial market uncertainty about the viability of the original chain.

The market ultimately validated Ethereum's hard fork as seen via the widening price delta between ETH and ETC. Over time, ETH has commanded an increasingly dominant premium representing more than just price appreciation-it reflects the market's recognition that Ethereum's willingness to take decisive action, prioritize user protection, and maintain community cohesion was the right choice.

The DAO incident institutionalised governance by debate and consensus, foundational for handling intense upgrades and issues in the future.

Ethereum vs Ethereum Classic: Price Delta Post-DAO Fork Chart 2
Source: Glassnode, Bitwise Europe; Data from June 2016 to July 2017

3. ICO Boom: Ethereum Becomes the Launchpad (2017)

Ethereum's first encounter with scale came in 2017, and it came fast. The ERC-20 standard turned Ethereum into the world's easiest token launchpad-allowing startups to raise capital directly from the crowd through Initial Coin Offerings (ICOs). Nine out of the ten largest projects that year chose Ethereum, collectively raising $603M, primarily in ETH.

But the velocity outpaced value. Many projects launched with little more than a whitepaper and a roadmap. The result was at once exhilarating, chaotic, and troublesome: a hypercompressed feedback loop of experimentation, speculation, and-ultimately-regulatory scrutiny. The SEC cracked down, halting the ICO boom, but not before Ethereum had already proven something deeper.

This short-lived frenzy became a stress test for Ethereum's infrastructure and a proving ground for novel fundraising models. Smart contracts scaled. Infrastructure held. Users learned. Founders iterated. The market rapidly separated substance from hype, offering a glimpse of what crypto capital formation could become.

More than just a fundraising frenzy, the ICO boom was Ethereum's first crypto product-market fit moment. Even failed ICOs revealed user preferences, tooling gaps, and latent demand. The frenzy seeded the platforms, frameworks, and developer muscle that would later give rise to more durable categories-like DeFi, NFTs, and tokenized assets.

In hindsight, the ICO cycle was a pivotal calibration event. It showed Ethereum could host global capital formation at scale, and established it as the de facto sandbox for crypto innovation.

The ICO Feedback Loop: Ethereum's Quarter-over-Quarter Innovation Testing Chart 3
Source: Etherscan, Bitwise Europe

4. DeFi Summer: A Parallel Finance System (2020)

After a bruising bear market from 2018-2020, Ethereum didn't just recover-it matured. DeFi Summer marked the protocol's second discovery of product-market fit. But unlike ICOs, where the focus was speculation, DeFi was different; The focus was real utility. Protocols like Uniswap, Aave, Compound, and Curve redefined capital markets from the ground up, enabling users to swap, lend, borrow, and earn yield-all without an intermediary.

The impact was immediate: DeFi overtook ERC-20s as the dominant transaction category on-chain. Token-denominated TVL, active addresses, DEX volumes, and gas spent turned Ethereum into a real-time dashboard of decentralized finance.

It was also a turning point for Ethereum's economic flywheel. As DeFi usage surged, so did fees, developer mindshare, and validator incentives. Ethereum's network began monetizing demand for its services: providing a programmable liquidity layer for financial activities without an intermediary.

Still, DeFi's vast scale exposed strain in the ecosystem. Congestion became chronic. Gas fees spiked to levels that priced out users and applications. Ethereum was winning, but it was also breaking, it became unusable. Fees per transaction increased to $13 in 2020, $68 in 2021 and $200 in 2022.

The protocol was struggling to provide service to a small segment of the world: crypto-expert users of DeFi protocols. If Ethereum planned to be the world's programmable computer, or the rails on which the future of finance would be built, something had to change. It couldn't handle the traffic.

Vitalik proposed a novel solution in a now-legendary blog post titled "Endgame." The post outlined a vision for how Ethereum would scale. If the central blockchain couldn't handle the demand, Ethereum would allow parallel tracks, called Layer 2 networks that would blossom alongside the main chain. Like access roads running along the highway, these Layers 2s could handle the traffic Ethereum could not, and would periodically post batches of transactions to the mainnet. This would prove to be a valuable, controversial, and a consequential pivot, and vastly change the economics of Ethereum, which we will get to later.

Ethereum Application Layer Composition by Fee Share Chart 4
Source: Etherscan, Bitwise Europe

5. The Flippening That Wasn't (2021-2025)

In 2021, Ethereum nearly flipped Bitcoin. The ETH/BTC ratio surged from ~5% to 83% in six months, marking the high point of a narrative cycle that cast Ethereum as the successor to Bitcoin-leading in users, fees, and developer activity. For a moment, it felt inevitable: Ethereum would overtake it in functionality and value.

The Flippening benchmarked Ethereum against Bitcoin. But the comparison was flawed.

Bitcoin is optimized for scarcity and monetary certainty-21 million tokens, held outside of government and institutional control. Ethereum is expressive, adaptable, and programmable. It was never built to be digital gold. Trying to “out-Bitcoin” Bitcoin was a category error.

The Flippening That Wasn't: Ethereum's Identity Crisis in Ratio Form Chart 5
Source: Etherscan, Bitwise Europe

The Flippening never materialized. The ratio retraced, bottoming at 11% by early 2025. On the surface, it looked like Ethereum had lost. In truth, Ethereum had learned.

There were significant changes to:

  • Monetary policy (The Burn),
  • Technological Architecture (Proof of Work to Proof of Stake),
  • Scaling approach (L2s),
  • Business model (transition from selling blockspace to data availability),
  • Roadmap (restructuring of the Ethereum Foundation).

The next half of the report takes the reader on a rollercoaster ride over the next four years. At first it was dark. Unintended consequences from upgrades and pivots plagued the protocol in every direction it took. Other competitors began to take market share and value from Ethereum. Sentiment was destroyed, developers were disenfranchised and users lost faith.

It took years of pain, deep reflection and realisation from The Foundation to pivot not just the roadmap, but Ethereum's entire posture-from a research-driven protocol drifting on reputation, to a product-focused institutionalised platform rebuilding trust through urgency, clarity, and execution.

6. The Burn Upgrade: A New Economic Engine (2021)

One challenge Ethereum faced as an investment was “why does it have value?” The protocol addressed this head-on in an upgrade called the London Hard Fork, or EIP-1559. EIP-1559 aligned network activity and protocol value via the introduction of base fee burns. A base fee, denominated in ETH, is the minimum fee part of every transaction made by a user. These get burned and taken out of circulating supply forever. ETH supply, therefore, became dynamically tied to usage-turning transaction demand into a disinflationary, and at times, deflationary force. The protocol was no longer just rewarding validators through inflating the circulating supply; it was in effect generating buyback pressure of its own token through burn mechanics.

The results were immediate and structural:

  • Annual ETH inflation rate dropped to -0.34% since the upgrade.
  • Post-Merge issuance moderated to +0.12% annualised, from 4% in its Proof of Work days.

While not always net-deflationary, the burn mechanism redefined ETH's monetary policy. It introduced a feedback loop where network adoption compresses supply, anchoring ETH's value in protocol utility. This reinforced Ethereum's "Ultrasound Money" narrative and differentiated its economic model from both Bitcoin and inflationary L1 competitors.

Ethereum Supply Since "The Merge": ETH Issued vs. Burned Chart 6
Source: Bitwise Asset Management with data from Coin Metrics and Ultra Sound Money. Data from September 15, 2022 to June 30, 2025.
Note: The Merge (Ethereum's transition to proof-of-stake validation) took place on September 15, 2022. As of June 30, 2025, the total supply of Ethereum was 120,866,777 ETH.

7. The Merge: Economic Security Reimagined (2022)

Ethereum's switch from Proof of Work to Proof of Stake was seven years in the making; it was even discussed and developed prior to Ethereum's launch due to environmental concerns with Proof of Work.

Changing the consensus protocol of a blockchain is hard. It is akin to swapping out the engine of an airplane in midflight. The process formally began in October 2020 with the deployment of the staking deposit contract and culminated on September 15, 2022, when the experimental staking chain (called the “Beacon Chain”) merged with Ethereum's execution layer. From that moment, Ethereum retired its miners and fully embraced staking as its transaction processing and security mechanism.

The upgrade provided multiple significant benefits to Ethereum and ETH holders:

  • Reducing energy consumption by 99%.
  • Escaped a doomed arms race against Bitcoin's industrial hashrate-180,000x larger-by embracing capital over computation for security.
  • It now costs at least $64bn to 51% attack the network today.
  • ETH became a yield-bearing asset-one capable of anchoring institutional portfolios.

In every respect-mainly economic security and institutional financialisation-Ethereum leveled up.

Ethereum Security: From Hashpower to Capital Commitment Chart 7
Source: Bitwise Europe, Glassnode, Full data from PoW to PoS transition

8. L2 Era Begins: The Rollup Pivot (2021–2023)

Ethereum's rollup-centric roadmap delivered scale. It prevented Ethereum from losing ground entirely to newer chains like Solana and Hyperliquid. It kept users in the ecosystem-even if not directly on the mainnet.

Coinbase's L2, Base, launched in 2023, which validated Vitalik's “Endgame” post. It quickly became the most active and largest rollup by TVL, trading volume, fees, and daily users. It also brought institutional credibility to Ethereum's L2 roadmap by putting a Nasdaq-listed name on-chain.

Ethereum's Scaling Strategy in Action: Average Daily Active Addresses on Layer-2 vs Ethereum Mainnet Chart 8
Source: Bitwise Asset Management with data from Coin Metrics and Token Terminal. Data from Q1 2020 to Q2 2025

With scale, came consequences.

The transition to Layer-2s fragmented the ecosystem across liquidity pools, tech stacks, and user experiences. Too many rollups, too little cohesion. Capital rotated out of Layer-1, R&D efforts splintered, and UX friction increased.

The Ethereum base layer also suffered as a result-activity dropped, and with it, fee burn. The “Ultrasound Money” narrative-dependent on high L1 throughput to drive ETH burn-began to lose traction.

L2 efficiency came at the cost of Ethereum's monetization model. Transaction frequency alone couldn't compensate for the diminished value of each transaction, leading to diminished value capture, rather than momentum.

9. Ethereum Wakes Up (2024 - 2025+)

By the end of 2023, Ethereum was an academically-driven behemoth–worth $276bn and down 50% from its peak–with no narrative or urgency. Other alternative Layer 1s were eating Ethereum's lunch.

Solana, for instance, which launched in 2020, was rivalling Ethereum's adoption metrics but with a more nimble developer base, start-up mindset focused on the user, and excited long-term institutional capital supporting architectural developments to applications building on top.

Ethereum, on the other hand, was tying themselves up in knots. It failed to compete with Solana and alt-L1s on cost, speed and UX-domains where those chains were purpose-built. Simultaneously touting its deflationary mechanics and “Ultrasound Money” thesis to rival Bitcoin on its monetary purity. As mentioned earlier, this also ended up failing due to L2 fee extraction, capital rotation, and R&D and mindshare splintering.

In chasing both rabbits, Ethereum caught none.

To make matters worse, internal voices began to criticize its long-term roadmap-like Justin Drake's Beam Chain proposal, which pushed full implementation into the 2030s. For many, the protocol felt more like a vision than a mission-a map that took the focus off building in the present, and in turn exposing Ethereum to the real possibility of falling behind the wayside forever.

After the backlash to this proposal, Ethereum's cultural posture began to change. The Ethereum Foundation announced leadership restructuring with a focus on three main objectives: scaling Ethereum's Layer 1, enhancing data availability through "blobs" to scale Ethereum's Layer 2s, and significantly improving user experience. Layoffs also occurred to streamline the Foundation and improve alignment and communication. The creation of a new business development and marketing function aims to enhance institutional adoption.

The Pectra upgrade, deployed in May 2025, doubled Blob throughput. The next upgrade, Fusaka, is expected in November 2025 and has been pulled forward marginally. As of writing, PeerDAS takes center stage-anchor scaling through Data Availability Sampling–to further extend throughput on top of the progress made in Pectra. Less critical upgrades like EOF remain but may be trimmed if needed to preserve timeline integrity. Scope reductions are strategic, not signals of slippage.

Ethereum has woken up, regained focus and found narrative clarity.

Ethereum's Business Model Transition Chart 9
Bitwise Europe, rwa.xyz, DeFi Llama

Ethereum has built the infrastructure to support a modular, institution-ready future. But with blob throughput scaling faster than usage, L2 settlement costs are falling-compressing one of Ethereum's few native revenue streams. It's a sign the system is working, but also a signal of what comes next. To fulfill its ambition as civilization-grade infrastructure, Ethereum must now solve for pricing power-turning blob fees into a dependable, elastic source of protocol revenue.

10. Institutional Inroads: ETF Era, Stablecoin Boom, Treasury Companies (2024 - 2025+)

The protocol's composability, decentralization, liquidity, brand-name, uptime and reliability made it a natural choice for institutions building on and using decentralised finance rails.

That shift accelerated dramatically with the passage of the Genius Act, the United States' first major stablecoin regulatory framework. Suddenly, Ethereum was the backbone of compliant, internet-native dollars.

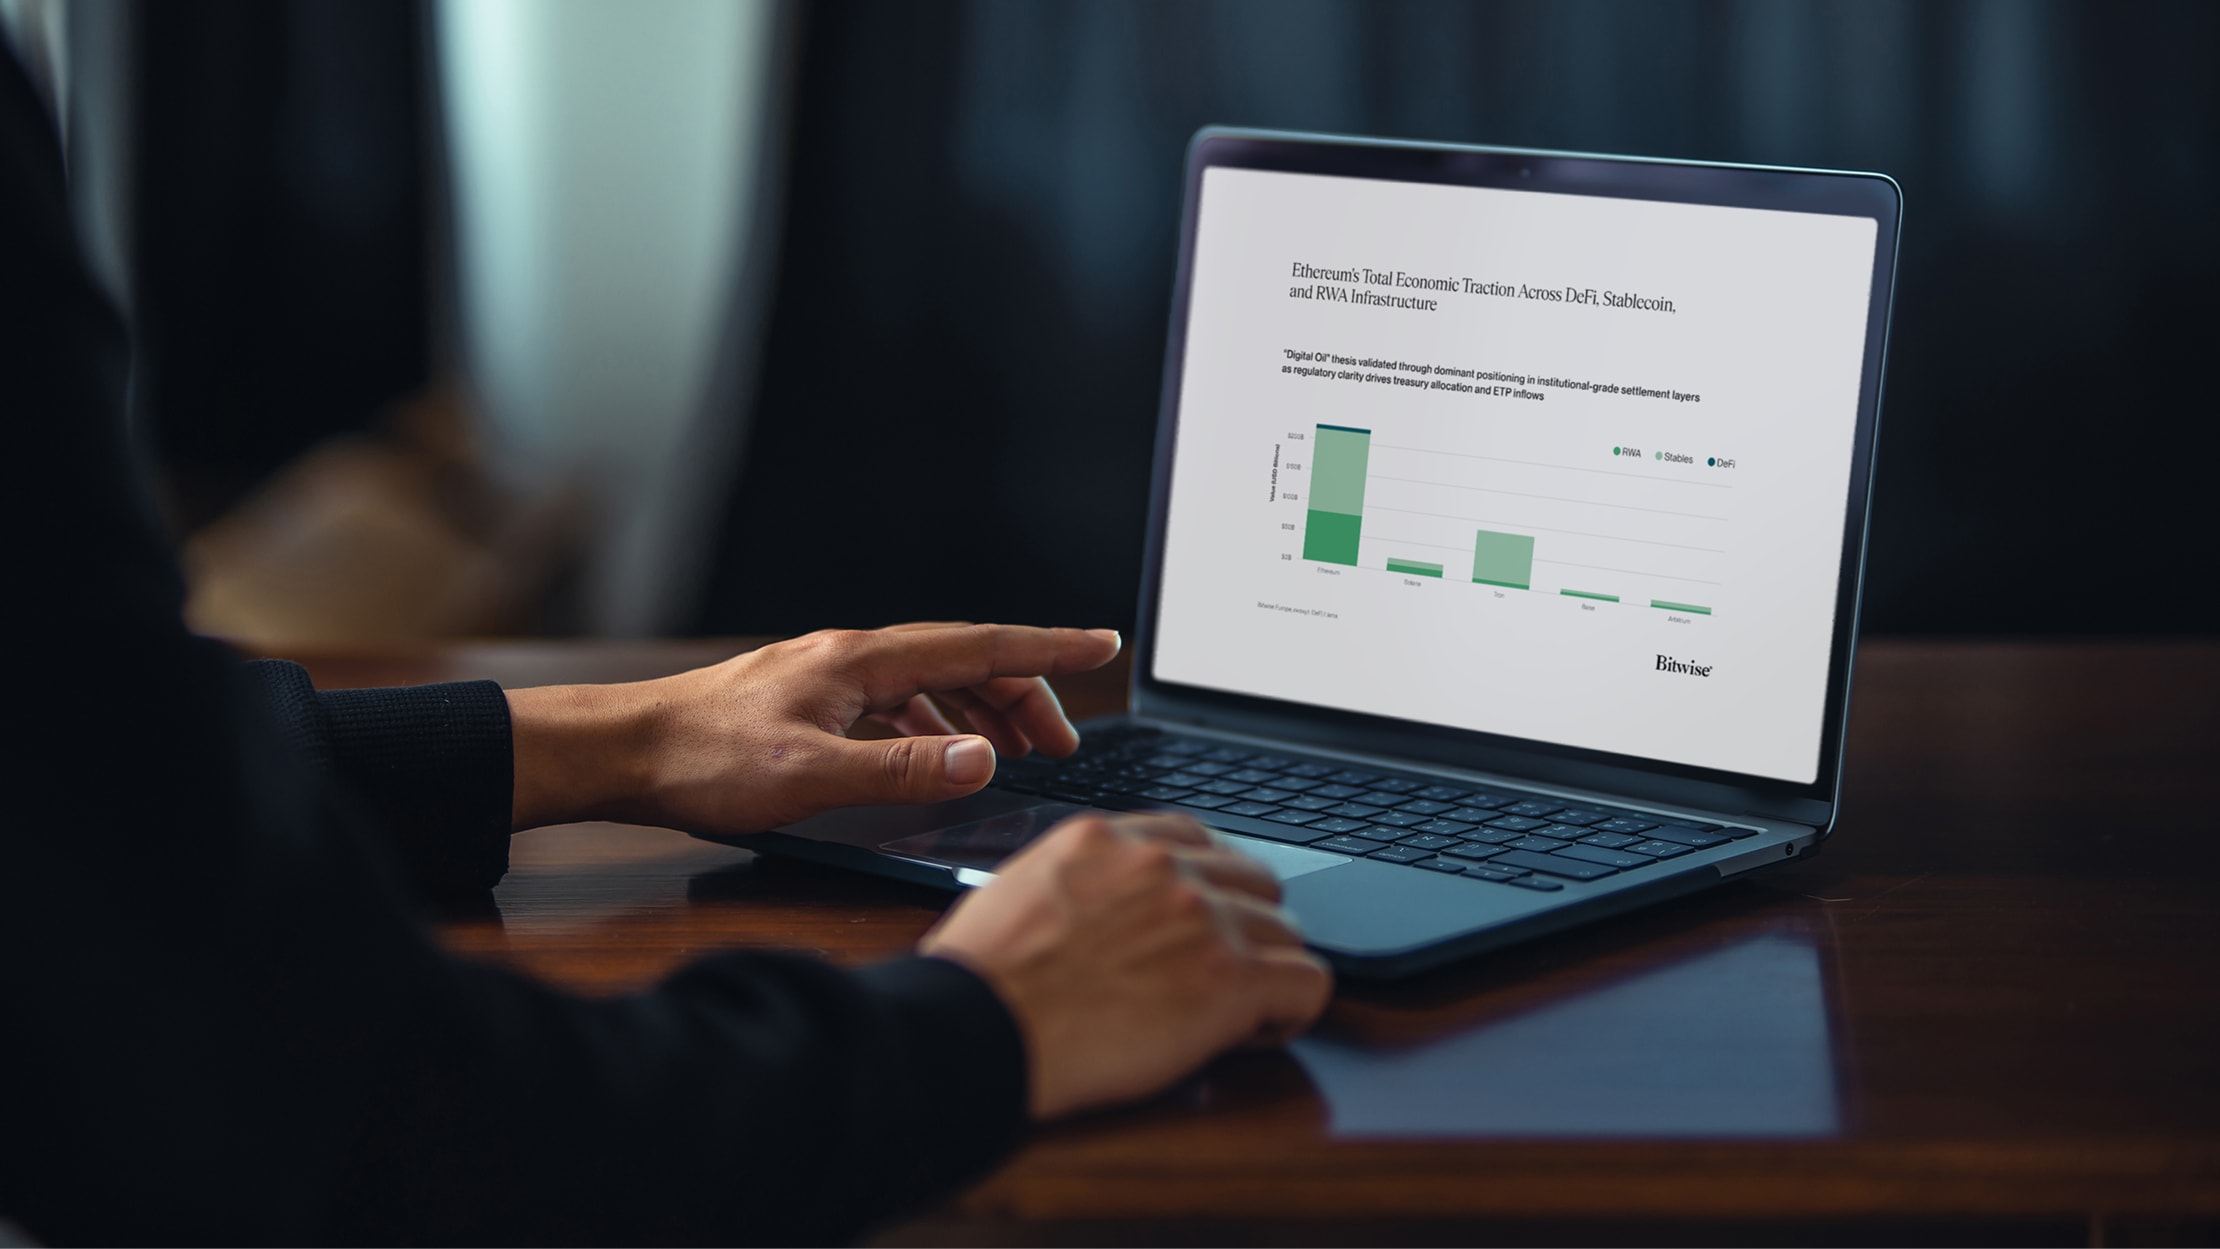
The majority of on-chain stablecoin and tokenized asset activity already lived on Ethereum. It had quietly captured more than 50% of the stablecoin market cap and over 55% of all tokenized value. The infrastructure was in place long before the legislation. The Act simply turned the spotlight on.

Institutions noticed. In the two weeks leading up to the bill's passage, ETHBTC rotation spiked-proof that investors were potentially front-running the regulatory shift.

Corporate adoption trends have accelerated, with Ether treasury companies gaining prominence and contributing to outperformance. The Ether Machine's combination with Dynamix Corp, a NASDAQ SPAC, launched with over 400,000 Ether valued at $1.45 billion at current prices-representing nearly half of the $3 billion held by publicly traded companies (886,060 Ether total).

Net ETH ETF flows have reached all-time highs, totalling $2.1 billion in the second week of July 2025. This is institutional recognition of Ethereum's role as "Digital Oil" powering tokenization and stablecoin infrastructure.

With regulatory clarity emerging, institutional onboarding and liquidity dominance, Ethereum's next wave of capital won't be chasing returns. It will be underwriting the system itself.

Ethereum's Total Economic Traction Across DeFi, Stablecoin, and RWA Infrastructure Chart 10
Bitwise Europe, rwa.xyz, DeFi Llama

Bottom Line

  • Ethereum’s greatest strength is its ability to adapt without losing coherence, evolving through cultural forks, architectural pivots, and economic redesigns that most platforms wouldn’t survive.
  • Ethereum’s architecture and economic model has pivoted a few major times to combine network adoption and value capture, and improve validator and user experience.
  • With regulatory clarity, stablecoin rails, DeFi dominance, RWA applications and ETF flows converging, Ethereum isn’t chasing the next narrative—it’s aiming to become the institutional foundation that underwrites it.

About Bitwise

Bitwise is one of the world’s leading crypto specialist asset managers. Thousands of financial advisors, family offices, and institutional investors across the globe have partnered with us to understand and access the opportunities in crypto. Since 2017, Bitwise has established a track record of excellence managing a broad suite of delta-one, index and active solutions across ETPs, ETFs, separately managed accounts, private funds, and hedge fund strategies, spanning both the U.S. and Europe.

Contact

General Inquiries europe@bitwiseinvestments.com
Institutional investors clients@bitwiseinvestments.com

Related articles you may like

Välkommen till Bitwise

Välj din plats

Välkommen till Bitwise

Bekräfta din plats för att hjälpa oss att leverera den webbupplevelse som är mest relevant för dig.

Välkommen till Bitwise

Bekräfta din plats för att hjälpa oss att leverera den webbupplevelse som är mest relevant för dig.

Välkommen till Bitwise

Bekräfta din plats för att hjälpa oss att leverera den webbupplevelse som är mest relevant för dig.

Switch to local website

We noticed you may be accessing this website from a different location than the one currently selected.

  • English
  • Deutsch
  • Italiano
  • Français
  • Svenska
Land
  • English
  • Deutsch
  • Italiano
  • Français
  • Svenska
Land
Viktigt meddelande:
Spridningen av informationen och materialet på denna webbplats kan vara begränsad enligt lag i vissa länder. Ingen del av informationen är riktad till eller avsedd för distribution till eller användning av någon person eller enhet i någon jurisdiktion (på grund av nationalitet, bosättningsort, hemvist eller registrerat kontor) där publicering, distribution eller användning av sådan information skulle strida mot lokal lagstiftning eller reglering.
Viktigt meddelande:
Du håller på att få tillgång till Bitwise Asset Managements webbplats. Baserat på din plats kommer ett klick på "Gå till den amerikanska webbplatsen" nedan att omdirigera dig till den USA-specifika webbplatsen.
Viktig information – vänligen läs innan du fortsätter

Denna webbplats drivs av Bitwise Europe GmbH ("Bitwise", "vi", "oss"). Informationen på denna webbplats är avsedd för privatinvesterare i Storbritannien och andra besökare i Storbritannien. Om du inte befinner dig i Storbritannien kan lokala lagar och regler skilja sig åt och materialet här kanske inte är lämpligt för dig.

Allt innehåll tillhandahålls endast i allmänt informationssyfte. Det utgör inte investeringsrådgivning, skatte- eller juridisk rådgivning, ett erbjudande eller en uppmaning att köpa eller sälja någon investering och får inte ligga till grund för ett investeringsbeslut. Du bör överväga om en investering är lämplig för dina omständigheter och, där så är lämpligt, söka oberoende professionell rådgivning.

Kryptotillgångar och produkter med exponering mot krypto är högriskinvesteringar. FCA kategoriserar kryptomarknadsföring för privatpersoner som Restricted Mass Market Investments (RMMI). Som sådan gäller ytterligare krav på framträdande plats, riskvarningar och risksammanfattningar för kommunikation med privatpersoner. Du kan förlora alla pengar du investerar.

Investeringar i kryptotillgångar eller många produkter med exponering mot krypto omfattas i allmänhet inte av UK Financial Services Compensation Scheme (FSCS) eller Financial Ombudsman Service (FOS). Du bör inte förvänta dig att vara skyddad om något går fel.

Tillgång till vissa sidor, funktioner eller transaktioner kan vara föremål för kundkategorisering och lämplighetsbedömningar som krävs enligt FCA:s regler. Vi kan be dig att genomföra kontroller eller avge förklaringar innan du kan fortsätta.

Där denna webbplats innehåller finansiell marknadsföring för krypto eller andra RMMI:er för privatpersoner, kommer du att se FCA:s föreskrivna riskvarning och en länk ("Ta 2 minuter för att lära dig mer") till FCA:s risksammanfattning som presenteras i en pop-up eller dedikerad sida. För enkelhetens skull kan du när som helst komma åt den sammanfattningen här.

Där utveckling visas är historisk utveckling ingen garanti för framtida resultat. Eventuella prognoser, mål eller framåtriktade uttalanden är i sig osäkra och kanske inte förverkligas. Avgifter och kostnader minskar avkastningen.

Avkastning kan minskas av avgifter, kostnader, spreadar och skatter. Skattebehandling beror på individuella omständigheter och kan förändras. Sök professionell rådgivning om du är osäker.

Där ett prospekt (inklusive grund- eller tilläggssprospekt) eller KID/PRIIPs KIID eller motsvarande tillhandahålls, är det regulatorisk information, inte marknadsföring. Dessa dokument ligger i allmänhet utanför Storbritanniens restriktion för finansiell marknadsföring.

I enlighet med FCA:s regler för högriskinvesteringar erbjuder vi inte incitament att investera (t.ex. värvningsbonusar, monetära eller icke-monetära förmåner) i förhållande till kryptomarknadsföring för privatpersoner.

Externa länkar tillhandahålls endast för enkelhetens skull. Vi kontrollerar inte och är inte ansvariga för tredjepartswebbplatser eller deras innehåll. Vi vidtar rimliga åtgärder för att säkerställa korrekthet men garanterar inte fullständighet, aktualitet eller tillgänglighet av webbplatsen eller dess innehåll; information kan ändras utan föregående meddelande.

Våra produkter eller tjänster kanske inte är tillgängliga i alla jurisdiktioner eller för alla investerare. Tillgång kan vara begränsad enligt lag. Du är ansvarig för att förstå och följa tillämpliga lagar och regler.

För frågor eller klagomål, kontakta: clients@bitwiseinvestments.com | Ytterligare kontakt- och juridisk information finns i våra Användarvillkor och Integritetspolicy.

Upphovsrätt & varumärken © 2025 Bitwise. Alla rättigheter förbehållna. Produktnamn, logotyper och varumärken är egendom som tillhör respektive ägare.

The selected location is intended only for people resident in that country. If you are accessing from the UK, you should not use this version of the website or access the products and services shown here, as they are not available in your country and may not be suitable for you.

We recommend switching to your local version of our website to view information relevant to your jurisdiction.

Avis Important

Les produits d’investissement domiciliés en Europe et présentés sur ce site sont des Exchange Traded Commodities (« ETC »), instruments financiers considérés comme des titres de créances complexes par l'Autorité des Marchés Financiers, présentant des risques difficilement compréhensibles par le grand public. À ce titre, leur distribution en France répond à des règles spécifiques. Il relève de la responsabilité des intermédiaires et investisseurs professionnels souhaitant offrir des ETCs à leurs clients de s'assurer que leur distribution auxdits clients est réalisée dans le respect de la réglementation française.

Viktig Information

Detta är en översättning av den engelskspråkiga originalversionen av ansvarsfriskrivningen. Vid eventuella avvikelser eller motstridigheter mellan denna översättning och den engelska originalversionen ska den engelska originalversionen, tillgänglig på bitwiseinvestments.eu/disclaimer/, äga företräde och vara juridiskt bindande.

Informationen som tillhandahålls i detta marknadsföringsmaterial är uteslutande avsedd i informationssyfte och utgör varken investeringsrådgivning, rekommendation eller uppmaning att ingå en transaktion.

Denna webbplats samt all dokumentation och övrig information som tillhandahålls på eller via den (gemensamt ”Webbplatsen”) publiceras av Bitwise Europe GmbH (”BEU” eller ”Emittenten”). Webbplatsen tillhandahålls uteslutande i illustrativt, pedagogiskt och informativt syfte och kan komma att ändras.

I den mån denna Webbplats utgör marknadsföring i den mening som avses i artikel 22 i förordning (EU) 2017/1129, i dess ändrade lydelse (”Prospektförordningen”), eller Regulation 3 i Public Offers and Admissions to Trading Regulations 2024, och det aktuella erbjudandet eller upptagandet till handel omfattas av en skyldighet att upprätta ett prospekt, har det tillämpliga prospektet offentliggjorts eller kommer att offentliggöras och finns eller kommer att finnas tillgängligt under avsnittet ”Resurser” på Bitwise Europes webbplats på bitwiseinvestments.eu/se/resources/.

Bitwise Europe GmbH, Thurn- und Taxis-Platz 6, 60313 Frankfurt am Main, Tyskland, registrerat i handelsregistret vid tingsrätten i Frankfurt am Main (Amtsgericht Frankfurt am Main) under nummer HRB 116604, är emittent av de Exchange Traded Products (”ETP:er”) som beskrivs på denna Webbplats, utgivna enligt ett tillämpligt grundprospekt godkänt av BaFin eller, i förekommande fall, av en annan behörig myndighet, i dess från tid till annan kompletterade lydelse, samt tillämpliga slutliga villkor. Slutliga villkor offentliggörs och lämnas in till den behöriga myndigheten i enlighet med tillämplig lagstiftning och kräver inget godkännande. Relevant produktdokumentation anger den behöriga myndighet som har godkänt det tillämpliga prospektet.

Att ett prospekt godkänns innebär att den behöriga myndigheten har granskat det utifrån tillämpliga standarder för fullständighet, begriplighet och konsekvens; godkännandet ska inte tolkas som ett stöd för eller en rekommendation av Emittenten eller ETP:erna. Om du överväger att investera i produkter utgivna av BEU bör du kontrollera med din mäklare eller bank att sådana produkter är tillgängliga i din jurisdiktion och lämpliga för din investeringsprofil. Ett beslut att investera ett belopp i en ETP som erbjuds av BEU bör beakta dina specifika förhållanden, efter att du inhämtat oberoende rådgivning i investerings-, skatte- och juridiska frågor.

Innan du investerar bör du läsa det relevanta grundprospektet, eventuella tillägg och tillämpliga slutliga villkor och, i synnerhet, avsnittet ”Riskfaktorer” för ytterligare information om de risker som är förknippade med en investering. Där så krävs bör du också läsa faktabladet enligt förordning (EU) nr 1286/2014 (Priip-förordningen), produktsammanfattningen enligt Consumer Composite Investments (Designated Activities) Regulations 2024, eller motsvarande produktinformation som är tillämplig i din jurisdiktion. Prospekt, tillägg, slutliga villkor, faktablad och övriga regulatoriska dokument av relevans för BEU:s ETP:er finns tillgängliga elektroniskt och kostnadsfritt under avsnittet ”Resurser” på Bitwise Europes webbplats på bitwiseinvestments.eu/se/resources/.

Tillgång till dessa dokument är, i enlighet med artikel 21.4 i Prospektförordningen respektive Prospectus Rules i FCA Handbook, inte villkorad av att en registreringsprocess har genomförts, av val av land eller investerartyp, av godkännande av Webbplatsens användarvillkor eller av någon ansvarsfriskrivning som begränsar rättsligt ansvar, eller av betalning av en avgift. I samband med visst innehåll kan varningar visas som anger de jurisdiktioner där ett erbjudande eller upptagande till handel sker; sådana varningar utgör inte ansvarsfriskrivningar som begränsar rättsligt ansvar.

Val av land eller investerartyp på denna Webbplats avgör vilket marknadsföringsinnehåll som kan visas. Ett sådant val utgör i sig inte en formell regulatorisk kundkategorisering, en bedömning av lämplighet eller passande karaktär, en bekräftelse av rättslig behörighet att investera, eller investeringsrådgivning.

Om Du Befinner Dig i Storbritannien, USA eller Kanada

Informationen på denna Webbplats utgör inte, och ska under inga omständigheter tolkas som, ett erbjudande att sälja eller en uppmaning att köpa värdepapper, eller något annat led i främjandet av ett offentligt erbjudande, i USA eller Kanada, eller någon delstat, provins eller territorium däri, där varken Emittenten eller dess produkter är auktoriserade eller registrerade för distribution eller försäljning och där inget prospekt från Emittenten har lämnats in till någon värdepapperstillsynsmyndighet. Varken denna Webbplats eller informationen i den får tas emot, överföras eller distribueras (direkt eller indirekt) till USA.

I Storbritannien tillhandahålls denna Webbplats uteslutande i informationssyfte och tillhandahålls under alla omständigheter i enlighet med undantaget från kravet, enligt Section 21 i Financial Services and Markets Act 2000, att kommunikation avseende inbjudan eller uppmuntran att bedriva investeringsverksamhet ska godkännas av en person auktoriserad av Financial Conduct Authority. Denna Webbplats riktar sig därför uteslutande till personer som omfattas av ett relevant undantag från begränsningen av finansiell marknadsföring enligt Financial Services and Markets Act 2000 (Financial Promotion) Order 2005, såsom professionella investerare (Article 19); förmögna privatpersoner (”high net worth individuals”, Article 48); förmögna bolag, icke-registrerade föreningar och liknande (Article 49); kvalificerade investerare (”sophisticated investors”, Article 50); självcertifierade kvalificerade investerare (Article 50A); samt sammanslutningar av förmögna eller kvalificerade investerare (Article 51). Personer som inte omfattas av något relevant undantag bör varken få tillgång till, förlita sig på eller agera utifrån denna Webbplats, utan bör istället gå till Webbplatsens version för privatinvesterare (”Private Investor”). Varken Emittenten eller dess produkter är auktoriserade eller reglerade av brittiska Financial Conduct Authority, och innehållet på denna Webbplats har inte godkänts av en person auktoriserad enligt Financial Services and Markets Act 2000.

Information om Publikationer och Sociala Medier

Kommunikation i sociala medier, inklusive inlägg på LinkedIn och X (gemensamt ”Sociala Medier”), kan utgöra marknadsföring, finansiell marknadsföring eller investeringsrekommendationer i den mening som avses i förordning (EU) nr 596/2014, Financial Services and Markets Act 2000, eller annan reglerad kommunikation, beroende på innehåll och den jurisdiktion där kommunikationen sprids. Om inte annat uttryckligen anges är sådan kommunikation inte avsedd att utgöra investeringsrådgivning eller en personlig rekommendation.

BEU vidtar alla rimliga åtgärder för att säkerställa att informationen i dokument och på Sociala Medier är korrekt och tillförlitlig; fel kan dock förekomma. I den mån det är tillåtet enligt tillämplig lag tillhandahålls dokument och material tillgängliga på Sociala Medier utan uttryckliga eller underförstådda garantier avseende riktighet, giltighet, aktualitet eller fullständighet. Ingenting i detta stycke utesluter eller begränsar ett lagstadgat eller regulatoriskt ansvar som inte lagligen kan uteslutas eller begränsas, inklusive skyldigheter avseende marknadsföring eller finansiell marknadsföring samt ansvar avseende ett prospekt eller annan regulatorisk information.

Om inte annat uttryckligen godkänts eller antagits av Bitwise Europe representerar kommentarer från medlemmar i onlinegemenskapen uteslutande dessa personers egna åsikter och godkänns inte av Bitwise Europe.

Risker med ETP:er och Kryptovalutor

En investering i en ETP som är säkerställd med en eller flera kryptovalutor, såsom de som ges ut av BEU, är beroende av den underliggande kryptovalutans utveckling, efter avdrag för kostnader; det kan dock inte förväntas att ETP:ns utveckling exakt motsvarar den underliggande tillgångens utveckling. Att investera i ETP:er är dessutom förenat med talrika risker, inklusive allmänna marknadsrisker relaterade till den underliggande tillgången, ogynnsamma prisrörelser, valuta-, likviditets-, operationella, juridiska och regulatoriska risker; investerare bör vara beredda på att förlora delar av eller hela det investerade beloppet.

ETP:er säkerställda med kryptovalutor är höggradigt volatila tillgångar och deras utveckling är oförutsägbar. Historisk avkastning är inte en tillförlitlig indikator på framtida avkastning. ETP:ers marknadspris varierar och de erbjuder ingen fast avkastning. Värdet på en ETP kan påverkas av växelkurser och prisutvecklingen för den eller de underliggande kryptovalutorna. Denna Webbplats kan innehålla framåtriktade uttalanden, inklusive uttalanden om Bitwise Europes uppfattning eller nuvarande förväntningar avseende utvecklingen för vissa tillgångsslag. Framåtriktade uttalanden är förenade med vissa risker, osäkerheter och antaganden, och det finns ingen garanti för att sådana uttalanden kommer att visa sig korrekta; faktiska resultat kan avvika väsentligt från vad som anges. Du bör inte förlita dig på framåtriktade uttalanden eller annan liknande information på denna Webbplats.

Kryptovalutor är höggradigt volatila och kända för sina extrema och snabba prissvängningar. Även om det kan finnas potential för betydande vinster riskerar du att förlora delar av eller hela ditt investerade kapital. Priset på kryptovalutor kan variera kraftigt och kan till exempel påverkas av globala och regionala politiska, ekonomiska eller finansiella händelser, regulatoriska händelser eller uttalanden från tillsynsmyndigheter, handels-, säkrings- eller andra aktiviteter från ett brett spektrum av marknadsaktörer, forkar av underliggande protokoll, samt störningar i infrastrukturen eller de medel genom vilka kryptotillgångar produceras, distribueras, förvaras och handlas. Kryptovalutors egenskaper och skillnaderna mellan tillämpliga regulatoriska standarder skapar potential för marknadsmissbruk. Priset på kryptovalutor kan även förändras till följd av föränderligt investerarförtroende avseende tillgångsslagets framtidsutsikter.

För en detaljerad översikt av de risker som är förknippade med kryptovalutor och, i synnerhet, med BEU:s produkter, hänvisas till prospektet och de slutliga villkoren, tillgängliga under avsnittet ”Resurser” på Bitwise Europes webbplats på bitwiseinvestments.eu/se/resources/. Du bör endast investera om du kan förstå och bedöma de risker som är förenade därmed. Om du är osäker på om en investering är lämplig för dig bör du rådgöra med en auktoriserad person som är specialiserad på rådgivning avseende investeringar, inklusive ETP:er säkerställda med kryptovalutor.

Avis Important

Les produits présentés sur ce site internet ne sont ni destinés à être distribués, ni accessibles aux investisseurs non-professionnels résidant en France. Toute information figurant sur ce site est fournie à titre informatif uniquement. Pour toute information complémentaire, veuillez contacter votre conseiller financier ou votre intermédiaire habituel.