- Performance: Elevated geopolitical risks and the resulting energy-driven inflation shock tightened financial conditions and created near-term headwinds for bitcoin. At the same time, strong institutional demand and reflationary dynamics provide a supportive medium-term backdrop, though elevated volatility and macro uncertainty remain significant constraints. Overall, markets remain highly volatile, with bitcoin caught between macro tightening pressures and structurally improving demand.
- Macro: Bitcoin is currently caught between rising inflation expectations (tailwind) and tightening financial conditions (headwind), with the latter largely already priced in. The asset has once again front-run macro deterioration - effectively pricing a recession ahead of traditional markets. With institutional demand rebounding and supply absorption strong, downside risk appears partially mitigated, though the potential for further declines persists. Additionally, any unexpected easing in monetary policy could act as an upside catalyst, though monetary policy developments remain inherently uncertain
- On-Chain: Bitcoin is showing early signs of structural stabilisation following a substantial repricing over the past six months alongside ongoing supply maturation dynamics. However, compressed investor profitability and elevated geopolitical risks continue to constrain trend persistence, with sentiment remaining broadly risk-off. As such, the market appears to remain in a consolidation regime, with confirmation of recovery likely requiring both macro stabilisation and a decisive reclaim of key on-chain pricing levels.
Chart of the Month

Source: Bloomberg, Bitwise Europe
Performance
Bitcoin and cryptoassets in March were predominantly shaped by a sharp escalation in geopolitical risks in the Middle East, culminating in a historic energy supply shock driven by the closure of the Strait of Hormuz. This resulted in a complex macro backdrop characterised by surging energy prices, rising inflation expectations, and a material tightening in financial conditions.
Bitcoin initially came under pressure during periods of acute geopolitical escalation, particularly around weekends when crypto markets remain one of the few liquid venues. This weakness coincided with broad-based de-risking across traditional assets, with equities and even gold experiencing notable drawdowns. However, performance over the month was not uniformly negative. Bitcoin demonstrated intermittent resilience and, at times, outperformed traditional assets such as global equities and gold, particularly as inflation expectations rose.
From a macro perspective, the dominant transmission channel was the surge in energy prices. The disruption of roughly 20% of global crude oil and LNG flows led to a sharp increase in inflation expectations, which in turn triggered a repricing of global monetary policy.
Rate markets shifted materially over the course of March - from pricing multiple rate cuts to increasingly anticipating rate hikes across major central banks, including the Fed, ECB, and Bank of England. This repricing tightened financial conditions, as evidenced by rising bond yields and stress in leveraged loans and private credit markets.
These tightening dynamics acted as a headwind for bitcoin in the short term, reinforcing its sensitivity to global liquidity conditions. At the same time, the macro environment also exhibited elements historically associated with stronger bitcoin performance. Rising inflation expectations and reflationary dynamics - partly driven by Chinese monetary expansion and compounded by geopolitical supply shocks - have historically coincided with bitcoin bull phases, although this relationship is not guaranteed to persist.
Importantly, bitcoin traded at a significant “macro discount” relative to global money supply throughout the month, suggesting a degree of already priced-in macro risk. While this may limit downside to some extent, the divergence from global liquidity trends has yet to fully resolve.
On the demand side, institutional flows provided a consistent source of support. Global bitcoin ETPs and treasury companies absorbed multiples of newly issued supply throughout March. Weekly inflows remained robust - even during periods of market stress - and cumulative institutional purchases over the past month significantly exceeded new bitcoin issuance. This structural demand dynamic appears to have cushioned downside volatility.
In cross-asset terms, bitcoin increasingly exhibited sensitivity to market-based inflation expectations, a relationship that has strengthened since 2020. This partially explains its relative resilience during certain phases of the energy-driven inflation shock. However, elevated volatility persisted as markets adjusted to the interplay between inflation, growth risks, and monetary tightening.
Within crypto markets, relative performance rotated throughout the month. Altcoin performance was inconsistent - ranging from broad outperformance in some weeks to complete underperformance in others - reflecting shifting risk appetite. Ethereum's relative performance versus bitcoin also varied, while assets such as TRON, Bitcoin Cash, and Hyperliquid intermittently emerged as outperformers.
Overall, March was characterised by a tension between short-term macro headwinds - driven by tightening financial conditions and recession risks - and medium-term tailwinds linked to reflationary dynamics and strong institutional demand. While historical patterns suggest that periods of elevated geopolitical risk may ultimately be followed by above-average bitcoin performance, near-term risks remain elevated, and market conditions are likely to stay volatile until greater clarity emerges on energy markets and monetary policy.


Bottom Line: Elevated geopolitical risks and the resulting energy-driven inflation shock tightened financial conditions and created near-term headwinds for bitcoin. At the same time, strong institutional demand and reflationary dynamics provide a supportive medium-term backdrop. Overall, markets remain highly volatile, with bitcoin caught between macro tightening pressures and structurally improving demand.
Macro Environment
Historically, bitcoin bull runs have coincided with expansions in the ISM Manufacturing Index - which has been in contraction for nearly 3.5 years and is only now showing tentative signs of recovery. This dynamic was also highlighted in our previous Chart-of-the-Month.
Similarly, bull markets have aligned with rising market-based inflation expectations, such as the US 5-year CPI swap rate. Both developments – the rise in the ISM Manufacturing Index and inflation expectations - are closely linked to energy prices.
US manufacturing is highly geared towards the energy sector, while energy itself remains a key driver of inflation expectations - making these relationships internally consistent.

But another important point to make is that the commodity rally that began in Q4 2025 was likely driven by a revival in Chinese economic activity at first, i.e. a demand impulse, as discussed in our previous BMI edition as well. More recently, supply disruptions stemming from geopolitical tensions in the Middle East have added a supply shock on top. Notably, commodities such as gold and copper reached all-time highs even before the more recent rise in energy prices.
That said, rising energy prices can become restrictive.
Historically, sharp increases in real (i.e. inflation-adjusted) oil prices - especially spikes exceeding 50% above trend - have been strong predictors of US recessions.
The latest move ranks among the four largest on record, comparable to 1974, 1990, and 2008.

gray areas denote NBER US recession periods
Daily WTI data post March 1983; interpolated monthly data prior Trend based on HP-filter
Recession odds for 2026 on major prediction markets like Kalshi have recently increased to 36% at the time of writing this report.
For bitcoin, this creates a two-sided dynamic.
On the one hand, rising inflation expectations such as CPI swaps have been a tailwind - particularly since the Covid crisis in 2020 as highlighted in one of our recent reports. On the other hand, higher energy prices have pushed sovereign yields higher and reduced expectations for monetary easing towards monetary tightening.
In fact, rising commodity prices – in particular energy prices – tend to translate directly into market-based inflation expectations such as CPI swaps and break-even rates and, ultimately, into higher bond yields.

*Commodity Inflation Index = Equal-weighted index of Brent and Copper
Recent upside surprises in US inflation and labour data have reinforced this shift, leading to a tightening in financial conditions as forward-looking rates markets have started to price out rate cuts.
For instance, Fed Funds Futures used to anticipate more than 2 rate cuts for the Fed in 2026 in February 2026 but have now completely priced out any rate cuts in 2026, at the time of writing this report in late March. This is both due to a gradual recovery in the US labour market but also due to strong upside inflation surprises more recently.

This tightening is increasingly visible across markets, including leveraged loans and private credit, which have experienced very notable outflows.
Bitcoin's drawdown since its October 2025 all-time high should also be viewed in this context as bitcoin tends to be one of the best assets to anticipate changes in financial conditions as the following chart demonstrates:

In fact, our analysis suggests that bitcoin has exhibited the largest “macro discount” on record-pricing in a significant tightening in financial conditions well in advance.
In other words, bitcoin has front-run the deterioration in macro expectations that is now becoming evident in forward-looking indicators such as the German ZEW and US regional Fed surveys.

Source: Bloomberg, Bitwise Europe
In other words, Bitcoin has, once again, acted as the “canary in the macro coal mine.”
In our analysis, bitcoin may be pricing a recession scenario - at levels comparable to the Covid downturn in 2020 - while many traditional assets have yet to fully adjust (Chart-of-the-Month).
Notably, this is historical pattern analysis, not a forecast, and relative performance may differ materially.
Source: Bloomberg, Bitwise Europe
This may explain why rising energy prices and inflation expectations are increasingly becoming a net tailwind at current price levels.
This may suggest that correlations between bitcoin and US equities could potentially decline going forward as US equities still need to adjust to the downside while bitcoin stays relatively resilient albeit volatile – a scenario we explored in our 2026 predictions as well last year.
Encouragingly, institutional demand has also returned. Corporate treasury companies and bitcoin ETPs have accumulated significant volumes of BTC over the past month, with MSTR accounting for more than half - representing multiples of daily new supply.
From a quantitative perspective, over the past six months, bitcoin's performance has been primarily driven by changes in financial conditions - namely monetary policy expectations and the US dollar. Looking ahead, a sustained improvement in bitcoin likely requires an easing in financial conditions.

However, as long as geopolitical risks and macro uncertainty remain elevated, financial conditions are likely to stay tight. That said, a significant share of this tightening - and associated downside risk - appears to have already been priced in.
Bottom Line: Bitcoin is currently caught between rising inflation expectations (tailwind) and tightening financial conditions (headwind), with the latter largely already priced in. The asset has once again front-run macro deterioration - effectively pricing a recession ahead of traditional markets. With institutional demand rebounding and supply absorption strong, downside risk appears partially mitigated, though the potential for further declines persists. Additionally, any unexpected easing in monetary policy could act as an upside catalyst, though monetary policy developments remain inherently uncertain.
On-Chain Developments
Everything is Relative:
Escalating geopolitical tensions between the US and Iran have severely disrupted oil flows from the Gulf region. The deterioration in regional stability has contributed to renewed volatility across global risk markets as discussed above.
Despite this backdrop, Bitcoin has demonstrated notable resilience, returning just a -3% loss since the onset of hostilities on February 28th. Contrastingly, major equity indices and key precious metals especially have underperformed over the same period, highlighting an emerging divergence in cross-asset performance.
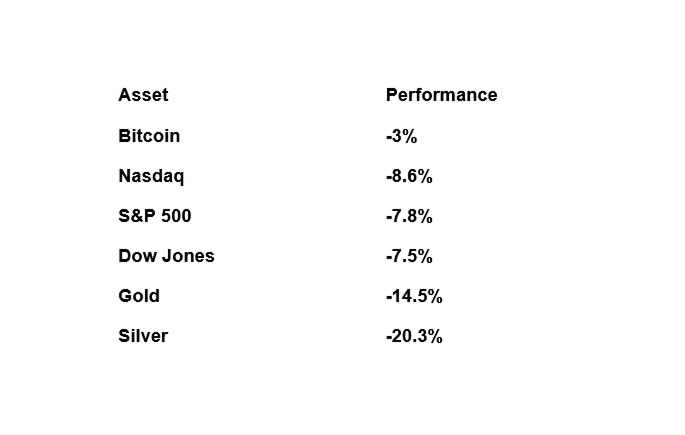
This divergence has driven a clear split in market interpretation. Some view Bitcoin's relative strength as a display of its macro hedging characteristics in periods of uncertainty. Others argue it reflects cyclical dynamics, with bouts of relief and relative resilience becoming increasingly probable following an extended period of downside repricing.

Assessing the percentage drawdowns from all-time highs provides useful context for these competing views. This provides insight into the magnitude of financial stress already absorbed by each asset prior to the geopolitical shock.
Bitcoin had already undergone a deep contraction of approximately -50%, whilst major equity benchmarks had only recently begun to widen towards drawdowns of around -5%.
Entering the geopolitical shock from an already weakened cyclical position has historically been associated with periods of relative stabilisation and intermittent relief rallies, as markets rarely trend in a single direction for prolonged periods.

Relative valuation frameworks also reinforce this asymmetry. The Mayer Multiple, which compares spot price to the 200-day moving average, shows that Bitcoin has remained within the lower percentiles of its historical range since the start of the year, reflecting persistently compressed conditions.
Equity markets, by contrast, began the year at elevated valuations and have only recently started to reprice as macro conditions deteriorated. This disparity suggests Bitcoin had already absorbed a larger share of tightening financial conditions over preceding months, whilst equities have only recently begun to reprice.
As a highly reflexive and liquidity-sensitive asset, Bitcoin typically responds earlier to shifts in risk appetite. Assets that have already undergone substantial valuation compression tend to exhibit reduced downside sensitivity as leverage and speculative positioning are progressively cleared, whereas markets trading closer to cycle highs often retain greater vulnerability to adverse catalysts.
On balance, Bitcoin's relative resilience since the onset of hostilities likely reflects diminished downside sensitivity following the multi-month drawdown rather than a direct response to geopolitical developments.

In Search of Momentum:
Whilst Bitcoin's price performance has been relatively resilient on a cross-asset basis, internal momentum conditions paint a more cautious picture. In this section, we turn to Bitcoin's more idiosyncratic drivers, examining the on-chain and structural dynamics that have shaped price action throughout the month.
Across the month, Bitcoin recorded a notable stretch of eight consecutive positive daily closes, a historically rare configuration observed on only 1.5% of trading days. Such streaks typically emerge during periods of improving short-term momentum.
Contrastingly, sustained uptrend structures remain largely absent across major equity indices and precious metals as of late. Both sectors demonstrated stronger trend persistence in Q4 2025 but have since shown signs of fatigue.

Nevertheless, investor profitability remained a key constraint on trend persistence. The MVRV Momentum metric, which uates current investor profitability relative to their yearly average, continues to signal severe balance sheet compression.
Similar readings have occurred predominantly in late-stage bear markets, where intermittent price recoveries emerge despite widespread investor impairment.
Historically, sustained upside momentum has often been associated with a broader recovery in profitability, as improving balance sheets reinforce risk appetite and capital deployment. In contrast, rallies that unfold under stressed conditions often struggle to generate follow-through. Residual supply from financially constrained holders tends to cap momentum as market participants adopt a “sell-the-rip” approach to de-risking.
The 8-day consecutive rally appeared consistent with this pattern, encountering sell-side resistance before reversing lower.

To complement this, we can uate key pricing levels which have historically marked the transition into risk-on regimes.
The True Market Mean at $78k estimates the average acquisition price of economically active investors by excluding dormant or lost supply, providing a cleaner view of underlying market cost basis. In parallel, the Short-Term Holder Cost Basis (STH-CB) at $83k reflects the average entry price of newer participants and has historically acted as a local regime boundary.
The $80k region also remains particularly significant, marking the November 2025 breakdown zone that has yet to be meaningfully retested. Notably, the True Market Mean, STH-CB, and this structural level all cluster within a tight $78k–$83k range, forming a dense cloud of potential resistance.
In the past, reclaiming key resistance levels has often coincided with transitions beyond consolidation phases. The $78k–$83k cluster may serve as one such reference point for market participants monitoring structural shifts.

HODLing Dominates Under the Surface:
Despite the elevation in geopolitical volatility and stressed investor balance sheets, early signs of structural stabilisation are emerging under the surface.
Combined realised profit and loss continues to compress, indicating that most coins that are transacting were acquired near the prevailing spot prices. This suggests that investors sitting deep in profit, as well as those carrying significant unrealised losses, remain reluctant to distribute supply. Current conditions appear neither attractive enough to incentivise profit-taking nor severe enough (due to acclimatisation of the range prices) to trigger widespread capitulation, reinforcing HODLing as the dominant market behaviour.
In contrast, a larger share of realised activity now originates from newer participants, whose positions are more sensitive to short-term price fluctuations. Ongoing whipsaw price action is therefore generating both speculative opportunity and financial stress within this cohort, contributing to fragile and locally volatile market conditions.

Market structure can be further assessed by analysing the average purchasing price of coins spent by Short- and Long-Term Holders. At present, mature investors are distributing supply from weaker financial positions than newer entrants, a relatively rare configuration.
As prolonged contraction pressures prices lower, newer participants accumulate coins at progressively more favourable cost bases, resulting in spending activity that clusters near recent spot prices. As of current, the average purchase price for a spent STH coin is $67.6k.
Alternatively, Long-Term Holders who accumulated during the topping distribution phase appear increasingly active on the sell-side, suggesting that capitulation pressures are becoming concentrated among the weakest segment of mature investors. Currently, Long-Term Holder supply is being spent at an average purchase price of $83.6k, whilst the spent price for coins moving in loss across the cohort is occurring around $99.8k.
Historically, such inversions in spending behaviour between newer and mature investors have tended to emerge during the later stages of bear market drawdowns.

Interestingly, Long-Term Holder supply continues to expand as dormant coins progressively age into the cohort. While weaker hands appear to be exiting, the majority of mature investors remain reluctant to distribute, suggesting that supply maturation is currently outweighing distribution pressures and reinforcing a progressively tighter market backdrop.
The rolling 155-day maturation threshold is soon to advance into the period of the November breakdown. Coins accumulated throughout the subsequent drawdown that have remained dormant are therefore approaching Long-Term Holder status, providing potential tailwinds for continued supply ageing in the months ahead.
On balance, this dynamic supports the broader HODLing thesis, with an increasing share of circulating supply becoming economically inactive rather than actively traded. Historically, declining supply churn has been a defining feature of late-stage bear markets and bottoming formations as coins migrate towards less price-sensitive and value driven investor with larger time horizons.

Furthermore, the Liveliness metric provides an elegant framework for assessing the long-term balance between coin-day destruction (spending) and coin-day creation (HODLing). By tracking the cumulative tendency of coins to remain dormant versus being spent, the metric offers a macro view of investor conviction and supply activity.
At present, Liveliness has begun to trend lower, further indicating that HODLing behaviour is once again becoming dominant across the current price range.

In the previous BMI edition, we introduced a framework tracking the volume of coins redistributed between the cycle high and eventual low, based on the premise that bear markets transfer supply from weak hands to higher-conviction investors.
As sell-side pressure becomes progressively exhausted, available supply tightens. Once marginal demand regains control, prices begin to rise, pushing dense clusters of coins back into profit, a dynamic that has historically initiated a reflexive shift towards improving risk sentiment and the inauguration of a new cycle.
At present, approximately 7.7 million BTC have been redistributed in the current cycle. Historically, bear market bottoms have formed once roughly 9–10 million BTC had changed hands. Under this framework, with the average transfer pace of this cycle around 48k BTC per day, this could suggest a base-case window of 1–2 months for redistribution dynamics to mature, extending towards 2–4 months under more conservative assumptions.
However, historical pattern analysis carries inherent limitations, and actual redistribution dynamics may diverge materially from prior cycles.
These dynamics suggest bottoming maturity is progressing through the lens of this framework, however, the broad uncertainty in geopolitical and macro conditions remains the main driver of financial markets.

Bottom Line: Bitcoin is showing early signs of structural stabilisation following a substantial repricing over the past six months alongside ongoing supply maturation dynamics. However, compressed investor profitability and elevated geopolitical risks continue to constrain trend persistence, with sentiment remaining broadly risk-off. As such, the market appears to remain in a consolidation regime, with confirmation of recovery likely requiring both macro stabilisation and a decisive reclaim of key on-chain pricing levels.
Bottom Line
- Performance: Elevated geopolitical risks and the resulting energy-driven inflation shock tightened financial conditions and created near-term headwinds for bitcoin. At the same time, strong institutional demand and reflationary dynamics provide a supportive medium-term backdrop. Overall, markets remain highly volatile, with bitcoin caught between macro tightening pressures and structurally improving demand.
- Macro: Bitcoin is currently caught between rising inflation expectations (tailwind) and tightening financial conditions (headwind), with the latter largely already priced in. The asset has once again front-run macro deterioration - effectively pricing a recession ahead of traditional markets. With institutional demand rebounding and supply absorption strong, downside risk appears partially mitigated, though the potential for further declines persists. Additionally, any unexpected easing in monetary policy could act as an upside catalyst, though monetary policy developments remain inherently uncertain.
- On-Chain: Bitcoin is showing early signs of structural stabilisation following a substantial repricing over the past six months alongside ongoing supply maturation dynamics. However, compressed investor profitability and elevated geopolitical risks continue to constrain trend persistence, with sentiment remaining broadly risk-off. As such, the market appears to remain in a consolidation regime, with confirmation of recovery likely requiring both macro stabilisation and a decisive reclaim of key on-chain pricing levels.
Appendix
Cryptoasset Market Overview


Cryptoassets & Macroeconomy

Cryptoassets & Multiasset Portfolios


Earliest data start: 2011-01-03; data as of 2026-03-24
Cryptoasset Valuations


On-Chain Fundamentals


Important Information
This publication constitutes a marketing communication and is provided for informational purposes only. It is intended solely for professional investors and is not suitable for retail customers distribution and reliance. It does not constitute investment advice, a personal recommendation, or an offer or solicitation to buy or sell any financial instrument.
This document (which may take the form of a presentation, press release, social media post, blog article, broadcast communication or similar instrument – collectively referred to as a “Document”) is issued by Bitwise Europe GmbH (“BEU” or the “Issuer”) and has been prepared in accordance with applicable laws and regulations, including those relating to financial promotions.
Bitwise Europe GmbH, incorporated under the laws of Germany, is the issuer of the Exchange Traded Products (“ETPs”) referenced in this Document under a base prospectus and the applicable final terms, as supplemented from time to time, approved by the German Federal Financial Supervisory Authority (BaFin). The approval of the prospectus by BaFin relates solely to the completeness, coherence and comprehensibility of the prospectus in accordance with the Prospectus Regulation and does not constitute an endorsement, recommendation or assessment of the merits of the products.
Capital at risk. Cryptoassets are highly volatile and involve a high degree of risk. The value of investments in cryptoassets and crypto-linked ETPs may fluctuate significantly, and investors may lose part or all of their invested capital. No capital protection or guaranteed compensation mechanism applies in respect of market losses.
Any investment decision should be made on the basis of the relevant base prospectus, the applicable final terms and the key information document, in particular the section entitled “Risk Warning” The base prospectus, final terms and additional risk information are available at: www.bitwiseinvestments.eu
Access to certain documents may require self-certification regarding your jurisdiction and investor status and may be subject to additional disclaimers and important information.
For further details, please refer to the full disclaimer available at: www.bitwiseinvestments.eu/disclaimer