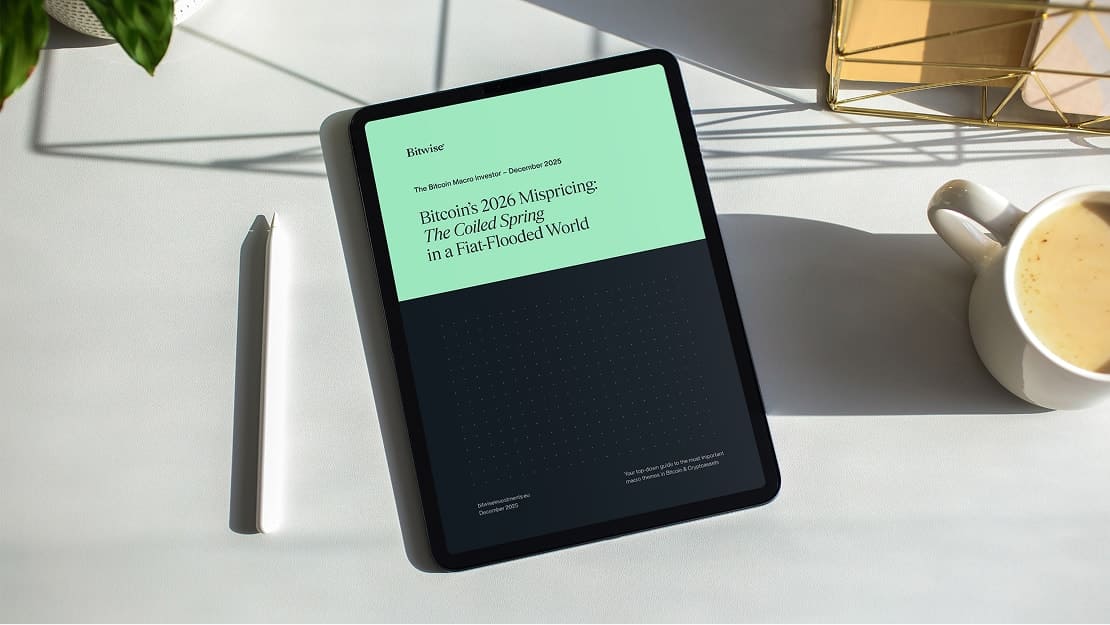


- Performance: Cryptoassets struggled through November as persistent risk-off sentiment, funding stress, and heavy profit-taking overshadowed supportive macro developments and resilient ETF-related inflows at the beginning of November. Yet the month’s deep capitulation, washed-out sentiment, and convergence toward key on-chain support levels collectively point to a maturing interim correction rather than a cycle top. With valuations attractive and macro conditions set to improve, the setup remains compelling heading into 2026.
- Macro: Despite recent price weakness, the macro backdrop remains decisively supportive for bitcoin as global liquidity reflates and monetary conditions ease across major economies. With bitcoin trading roughly 66% below its model-implied equilibrium relative to global money supply - and gold significantly overextended - the setup favors a rotation back into bitcoin as growth indicators improve. Overall, sentiment, valuation metrics, and macro momentum collectively point to a broadly undervalued asset and an extended bitcoin cycle into 2026.
- On-Chain: Bitcoin’s latest pullback remains consistent with a maturing bull-market structure, with volatility-adjusted drawdowns sitting near historical medians and far more contained than in prior cycles. Key cost-basis levels across on-chain metrics, ETFs, and corporate treasuries cluster tightly between $81k–$75k, offering significant support and defining the boundaries of a maximum-pain scenario. Taken together, pricing signals, structural stability, and deeply depressed valuation metrics all point to a market trading in a substantially undervalued zone which already offers attractive opportunities to increase exposure again.
Chart of the Month

Performance
Throughout November, cryptoassets consistently underperformed traditional financial markets amid a persistent and broad-based risk-off environment. Despite several constructive macro and regulatory developments - most notably renewed monetary easing by the Federal Reserve and incremental institutionalisation via US-listed crypto ETFs - sentiment across digital assets remained fragile as profit-taking, funding stress and episodic macro shocks weighed on risk appetite.
The month began with encouraging news: US–China trade tensions showed signs of easing, the Fed delivered another rate cut and confirmed the formal end of QT, and the first US spot Solana ETFs launched with exceptionally strong inflows. Bitwise’s BSOL ETF dominated early demand, helping push global SOL ETP flows above $400 million - the second-largest weekly inflow on record - and underscoring growing institutional engagement. Historically supportive seasonality for bitcoin, together with the backdrop of a decisive global monetary easing cycle, had set the stage for stronger performance; however, these tailwinds failed to offset mounting risk aversion.
Instead, cryptoassets traded lower through the month as stress in US interbank funding markets, hawkish rate expectations and weakness in megacap tech stocks spilled over into digital assets. Alternative labour-market data pointed to possible job losses in the US, and concerns over the government shutdown further weighed on liquidity conditions. Although these dynamics ultimately strengthened the case for renewed Fed easing - and even the potential return of QE - investors remained defensive.


Market psychology deteriorated sharply. Both the Crypto Fear & Greed Index and US equity sentiment measures fell into “extreme fear,” approaching levels last seen during the FTX collapse and the Covid crash. On-chain data reinforced this picture: short-term holders realised their heaviest losses since major past dislocations, and long-term holders offloaded roughly -240k BTC in November.
Rumours of bitcoin sales by Michael Saylor's Strategy Inc. (MSTR) added to the unease. Importantly, many of these indicators flashed contrarian signals, showing rising seller exhaustion and historically favourable forward return conditions.
Toward the end of the month, loss-taking among short-term holders accelerated further, culminating in the largest capitulation of this cohort in bitcoin's history.
Yet this capitulation coincided with early signs of stabilisation. Bitcoin approached a cluster of key support levels, including the aggregate cost basis of US spot Bitcoin ETFs (~$81k) and the on-chain true market mean (~$82.5k), which had repeatedly acted as strong floors during prior corrections. ETF flows turned positive again, with record trading volumes signalling renewed investor engagement.
Despite negative year-to-date performance and heightened fears of a potential cycle top, several structural factors continued to argue against a bear-market transition:
Global liquidity growth remains robust, institutional demand has reshaped post-Halving supply dynamics, and valuations show no evidence of a blow-off phase.
Instead, bitcoin appears undervalued across multiple on-chain and sentiment metrics, and the drawdown itself remains consistent with prior bull-market corrections in both depth and duration.
Overall, November was characterised by macro-driven risk aversion, significant sentiment washout and heavy but largely healthy capitulation dynamics.
With valuations attractive, positioning cleansed and underlying macro conditions set to improve, the balance of evidence suggests that the current consolidation represents an interim correction within a broader ongoing bull market.
Bottom Line: Cryptoassets struggled through November as persistent risk-off sentiment, funding stress, and heavy profit-taking overshadowed supportive macro developments and resilient ETF-related inflows at the beginning of November. Yet the month's deep capitulation, washed-out sentiment, and convergence toward key on-chain support levels collectively point to a maturing interim correction rather than a cycle top. With valuations attractive and macro conditions set to improve, the setup remains compelling heading into 2026.

Macro Environment
The fundamental macro environment continues to be supportive of bitcoin despite the negative price action.
Global liquidity conditions continue to shift meaningfully as major economies pivot toward renewed monetary and fiscal accommodation.
The United States is preparing $2,000 stimulus cheques to low-income Americans while simultaneously issuing nearly $1.9 trillion in Treasuries per year, and the Federal Reserve has confirmed that Quantitative Tightening (“QT”) will formally end on December 1st.
Japan is moving forward with a substantial $110 billion stimulus package, and Canada has restarted its Quantitative Easing (“QE”) programme already.
In parallel, China has approved an unprecedented $1.4 trillion fiscal initiative. Against this backdrop, global M2 money supply has reached a record $137 trillion, and more than 320 rate cuts have been executed worldwide over the past 24 months. Collectively, these developments underscore a decisive turn toward global reflation and a reversal of the previously restrictive macro regime.
Although bitcoin has recently deviated significantly from the trajectory of global money supply, we expect this relationship to reassert itself as we are moving into 2026.
The reason is that bitcoin tends to exhibit a so-called cointegration relationship with global money supply, i.e. gyrates around it over the medium- to long-term.
This implies that deviations of bitcoin from global money supply in the short-term are possible but bitcoin tends to mean-revert to global money supply over time again as the chart below shows:

It is important to highlight that bitcoin is currently undershooting global money supply by around -66% (“mispricing”).
In other words, based on this cointegration model, bitcoin has around +194% hypothetical upside if it catches up to the equilibrium price implied by global money supply.
(Model-implied price ~$270k; Hypothetical Upside = (1 / (1 - 0.66)) -1 = +194.1%).
Simply put, bitcoin is currently undervalued relative to the amount of global money supply.
Bitcoin tends to be the best barometer for global monetary dilution due to its absolute scarcity. That being said, it is fair to say that gold has probably received the lion's share of global monetary dilution in 2025 so far which is evident in its strong outperformance relative to bitcoin and other hard assets.
However, in this context, it is worth pointing out that gold currently significantly overshoots the trajectiory of global money supply by approximately +75%.

We still expect that a renewed risk-on rally with rising global risk appetite should lead to a change in performance leadership between bitcoin relative to gold again as highlighted in our previous Bitcoin Macro Investor report in November.
Relative valuations between bitcoin and gold are also very attractive which further strengthens the case for an imminent rotation with potentially very large performance effects on bitcoin as highlighted in one of our Crypto Market Compass reports in late October.

All of these observations stil support our rotation hypothesis from gold to bitcoin as laid out in previous reports.
In general, valuation metrics for bitcoin already imply a significant undervaluation and therefore very attractive entry points for investors as highlighted in our on-chain section below.
What is more is that leading indicators like regional manufacturing surveys as the New York Empire State Manufacturing survey continue to signal a renewed acceleration in US economic momentum and also a pick-up in the ISM Manufacturing Index.

It is key to understand that bitcoin currently still signals a recessionary economic growth. Based on our models, we think that bitcoin currently prices a sub-50 ISM Manufacturing Index and no material acceleration. To the contrary, the latest price action implies a deeper decline into contractionary territory.
More specifically, we think that bitcoin and other major cryptoassets underprice leading macro indicators by around -1 standard deviation which is alerady approaching levels of underpricing seen in 2022 (FTX) or 2020 (Covid).
In other words, bitcoin is already pricing in recessionary growth picture which we think is too excessive.
So, even if bitcoin was the “canary in the macro coal mine” and was pricing in a less favourable macro environment, a lot of bad news seems to be priced in already.
On the bright side, the pessimistic pricing limits further downside if growth should surprise to the upside (as we expect due to the previous easing in global monetary policy and financial conditions).
The following chart highlights that major economies will most-likely continue to expand at a solid pace well into 2026 due to the previous number of rate cuts around the globe.

OECD leading indicators are also pointing towards a renewed global expansion. So, it's not only confined to the US but one can see the acceleration on a global basis.
The implication is that we are most likely looking at an extended bitcoin cycle and no bear market over the coming 12 months.
The rationale: bitcoin should start to price in a more benign growth picture as growth indicators will continue to surprise to the upside and capital rotates from gold to bitcoin in a renewed risk-on environment.
What is more is that bitcoin appears to be cheap both in absolute terms (MVRV z-Score) and also relative to its own scarcity (BAERM – see appendix).
All in all, this implies a broad-based undervaluation and mispricing of bitcoin and cryptoassets right now as highlighted here as well.
In this context, it is also worth noting that we haven't seen any kind of blow-off top / excessive valuations in this cycle like in previous bull cycles as highlighted in this post by Adam Back. This also implies an extended bull cycle.
Besides, our own Cryptoasset Sentiment Index has flashed contrarian buying signals on both October 10th (during the liquidation event) and more recently on the 21st of November. The Crypto Fear & Greed Index published by alternative.me also implies an excessively bearish market sentiment.
Bottom Line: Despite recent price weakness, the macro backdrop remains decisively supportive for bitcoin as global liquidity reflates and monetary conditions ease across major economies. With bitcoin trading roughly 66% below its model-implied equilibrium relative to global money supply -and gold significantly overextended - the setup favors a rotation back into bitcoin as growth indicators improve. Overall, sentiment, valuation metrics, and macro momentum collectively point to a broadly undervalued asset and an extended bitcoin cycle into 2026.
On-Chain Developments
Drawdown Analysis
Across Bitcoin's 16-year evolution, it has transformed into a mature and highly liquid macro asset. Its growth has materially altered both its return profile and its volatility structure, with the current bull market exhibiting far more measured behaviour than previous cycles. Volatility has compressed across all time horizons and market advances have become increasingly orderly. Quarterly performance in the current cycle has peaked at 84%, compared with 428% and 261% during the 2018 and 2021 cycles, underscoring its increasing stability and diminshing returns profile.

We believe that this latest correction still represents an interim bull market correction as previous corrections have been quite similar both in terms of depth and duration:

Consider the following statistics (based on closing prices):
- Avg drawdown (peak to trough): -26.9% / Range: -38.6% to -20%
- Avg length: 34 days / Range: 1 day to 177 days
- Latest correction: -32.7% and 47 days
When normalising drawdowns from the all-time high by the 1-month realised volatility, we can account for the structural compression in volatility seen across cycles and therefore compare the current drawdown more fairly with previous periods.
On this basis, the preak of this drawdown sits in the 44th percentile, suggesting that market stress was broadly in line with median histroical conditions.
Previous cycle lows were characterised by far deeper volatility-adjusted drawdowns. The table below illustrates how drawdowns at various historical percentiles would translate into today's price structure:

Given the evolution of market structure and investor composition, we expect the drawdown profile of this cycle to be substantially more contained relative to earlier cycles.
The stair-stepping market pattern, driven by alternating phases of accumulation and distribution, has produced a far more stable structural foundation. Additionally, price performance throughout the cycle has been less euphoric than in previous bull markets, which implies that downside conditions are likely to exhibit similar maturity, with contractions remaining more controlled than in prior years.
Key Pricing Levels
With the market now at a point of extreme fear, we can utilise key pricing levels, spanning on-chain metrics, as well as the spot ETFs and Treasury Company complex to aid in identifying areas of support.
Initially, we can employ two key cost-basis metrics, the True Market Mean and the Active Investor Price, both of which aim to measure the average purchasing price of active investors. Notably, the market found support at the Active Investor Price during the Yen-Carry-Trade-Unwind in August 2024, marking the precise point of the bottoming formation.
During the recent contraction, price broke below both key cost-basis levels, briefly trading through the Active Investor Price ($88k) and the True Market Mean ($82k). However, the market ultimately found support at the True Market Mean, and the subsequent recovery back toward $91k indicates a meaningful defence of investor cost-basis. Since these models reflect market fair value, the return to this zone suggests a full reset in investor sentiment and a broad cleansing of the exuberance that characterised the all-time-high period.

Furthermore, we can employ the Short-Term Holder Cost-Basis (STH-CB) which represents the average acquisition price for new, price sensitive investors in the market, allowing for insight into their sentiment. To add further context, we apply standard deviation bands around this cost basis to identify when these participants are significantly underwater, or holding substantial profit.
Across the market contraction, the spot price reached the −2σ band at $81k. Reaching this level is exceptionally rare, with fewer than 0.02% of trading days closing below it, signalling a period of historically significant unprofitability for new investors. The market has since recovered to the −1σ level at $91k, and it would be a constructive development to see this key pricing zone reclaimed decisively, providing initial signs of an improving market structure.

Interestingly, the US spot Bitcoin ETF average cost basis also sits near these levels at $81k, providing a notable degree of confluence. This level acted as key support during the previous macro stress events noted earlier, and has again served as strong support during the recent contraction. This underscores the growing influence of the ETF complex on Bitcoin price behaviour and marks it as an important threshold to observe.

Strategy remains the premier corporate treasury holder of Bitcoin and has largely catalysed the recent renaissance in the formation of new treasury-based investment vehicles. Notably, Strategy accounts for more than 60% of the BTC supply held across these entities, which makes its average acquisition price, currently at $75k, an important psychological level to monitor going forward.

We therefore expect the highest probability outcome is for the market to begin forming a bottom within the $81k to $75k channel, where a strong confluence exists between the US spot Bitcoin ETF cost basis, the MSTR cost basis and the True Market Mean.
An Undervalued Market
With market fear at extreme levels, we assess key technical and on-chain valuation metrics to assess for potential undervaluation and opportunity. Below are the list of metrics we shall uate:
- The Mayer Multiple serves as a widely referenced momentum gauge and often defines the boundary between longer-term trend expansion and contraction.
- The AVIV Ratio measures the average profit or loss held across active investors in the market and provides insight into the pressure or euphoria the common market participant is experiencing.
- The STH-MVRV captures the average profit or loss held across recent investors and has historically acted as the dividing line between local bullish and bearish regimes.
Here, we apply a 90-day Z-score of these metrics to capture quarterly performance and shorter-term cycle dynamics, while the 1-year and 2-year Z-scores highlight intermediate inter-cycle trends. Finally, the 4-year Z-score provides a holistic perspective and helps identify periods of significant under or overvaluation across the broader market cycle.
Across these valuation metrics, the Z-score percentiles indicate that the market is severely undervalued. Short- and medium-term Z-scores sit deeply below their historical averages, while long-term measures also remain subdued, suggesting that Bitcoin is trading in a structurally discounted zone across multiple time horizons.

Bottom Line: Bitcoin’s latest pullback remains consistent with a maturing bull-market structure, with volatility-adjusted drawdowns sitting near historical medians and far more contained than in prior cycles. Key cost-basis levels across on-chain metrics, ETFs, and corporate treasuries cluster tightly between $82k–$75k, offering significant support and defining the boundaries of a maximum-pain scenario. Taken together, pricing signals, structural stability, and deeply depressed valuation metrics all point to a market trading in a substantially undervalued zone which already offers attractive opportunities to increase exposure again.
Bottom Line
- Performance: Cryptoassets struggled through November as persistent risk-off sentiment, funding stress, and heavy profit-taking overshadowed supportive macro developments and resilient ETF-related inflows at the beginning of November. Yet the month’s deep capitulation, washed-out sentiment, and convergence toward key on-chain support levels collectively point to a maturing interim correction rather than a cycle top. With valuations attractive and macro conditions set to improve, the setup remains compelling heading into 2026.
- Macro: Despite recent price weakness, the macro backdrop remains decisively supportive for bitcoin as global liquidity reflates and monetary conditions ease across major economies. With bitcoin trading roughly 66% below its model-implied equilibrium relative to global money supply - and gold significantly overextended - the setup favors a rotation back into bitcoin as growth indicators improve. Overall, sentiment, valuation metrics, and macro momentum collectively point to a broadly undervalued asset and an extended bitcoin cycle into 2026.
- On-Chain: Bitcoin’s latest pullback remains consistent with a maturing bull-market structure, with volatility-adjusted drawdowns sitting near historical medians and far more contained than in prior cycles. Key cost-basis levels across on-chain metrics, ETFs, and corporate treasuries cluster tightly between $81k–$75k, offering significant support and defining the boundaries of a maximum-pain scenario. Taken together, pricing signals, structural stability, and deeply depressed valuation metrics all point to a market trading in a substantially undervalued zone which already offers attractive opportunities to increase exposure again.
Appendix
Cryptoasset Market Overview


Cryptoassets & Macroeconomy


Cryptoassets & Multiasset Portfolios


Cryptoasset Valuations


On-Chain Fundamentals


Important Information
This publication constitutes a marketing communication and is provided for informational purposes only. It does not constitute investment advice, a personal recommendation, or an offer or solicitation to buy or sell any financial instrument.
This document (which may take the form of a presentation, press release, social media post, blog article, broadcast communication or similar instrument – collectively referred to as a “Document”) is issued by Bitwise Europe GmbH (“BEU” or the “Issuer”) and has been prepared in accordance with applicable laws and regulations, including those relating to financial promotions.
Bitwise Europe GmbH, incorporated under the laws of Germany, is the issuer of the Exchange Traded Products (“ETPs”) referenced in this Document under a base prospectus and the applicable final terms, as supplemented from time to time, approved by the German Federal Financial Supervisory Authority (BaFin). The approval of the prospectus by BaFin relates solely to the completeness, coherence and comprehensibility of the prospectus in accordance with the Prospectus Regulation and does not constitute an endorsement, recommendation or assessment of the merits of the products.
The market analyses, views and scenarios presented reflect the assessment as of the date of publication and are based on information considered reliable. However, no representation or warranty is made as to their accuracy or completeness. Forward-looking statements involve risks and uncertainties and are not guarantees of future performance. Past performance is not a reliable indicator of future results.
Capital at risk. Cryptoassets are highly volatile and involve a high degree of risk. The value of investments in cryptoassets and crypto-linked ETPs may fluctuate significantly, and investors may lose part or all of their invested capital. No capital protection or guaranteed compensation mechanism applies in respect of market losses.
Any investment decision should be made solely on the basis of the relevant base prospectus, the applicable final terms and the key information document, in particular the section entitled “Risk Warning”. The base prospectus, final terms and additional risk information are available at: www.bitwiseinvestments.eu
Access to certain documents may require self-certification regarding your jurisdiction and investor status and may be subject to additional disclaimers and important information.
For further details, please refer to the full disclaimer available at: www.bitwiseinvestments.eu/disclaimer


