Fusaka Won’t Solve Ethereum’s Revenue Challenge; It Will, However, Make The Blockchain More Useful

Fusaka Won’t Solve Ethereum’s Revenue Challenge; It Will, However, Make The Blockchain More Useful | Bitwise
  • Fusaka’s impact is more positive for user experience and L2 margins than it is on Ethereum’s revenue generation.
  • We expect post-Fusaka blob fees to generate over the next-twelve-months between 5.39 ETH ($16k) and 78.2 ETH ($234k).
  • Over time, blob fees will continue to get cheaper from continued increases in blob counts per block and a continued decline in execution fees.

Ethereum’s approach to scaling is deliberate. Rather than forcing every transaction to compete for block space on the main network, most activity is expected to take place on Layer 2s (L2), which periodically settle back to Ethereum for storage and transaction finalisation reasons. The first major step in this strategy arrived in March 2024 with the Ethereum Improvement Proposal (EIP)-4844. The upgrade introduced blobs, which were designed as a new data type built specifically for rollups. Because blobs are only stored temporarily on Layer 1 nodes, they can be priced far more cheaply, materially reducing costs for L2 users.

Blob prices have their own market to determine cost to users, and were originally designed to adjust smoothly with demand. In practice, however, realized blob fees were bipolar: They  collapsed towards zero during quiet periods and spiked sharply when usage surged. This was not optimal from a user or L2 point of view.

The Fusaka upgrade, implemented on 3 December 2025 through EIP-7918, introduced a meaningful evolution of Ethereum's L2 fee pricing mechanics. It established a pricing "floor" whereby the effective blob price is the higher of two values: either 1/16th of the execution gas base fee or the price determined by the blob market’s own supply and demand. 

In effect, if the 1/16th floor value is higher than the raw blob market price, the cost is set by that floor. Conversely, in a scenario where the 1/16th floor is lower than the natural market demand for blobs, the price remains determined by the blob fee market itself.

Some observers have argued (or, at least, hoped) that this minimum blob fee would significantly boost Ethereum revenues over time.  This Espresso shows that to be false. While Fuuska   the floor on blob fees, the marginal benefit is offset by continued scaling upgrades, which have been (and we believe will continue to) keep blob costs trending lower. As a result, we forecast that next-twelve-month blob fees will barely contribute to Ethereum’s overall revenue. The more durable impact lies in the second-order effects of greater fee predictability, which are likely to be far more meaningful for Layer 2s and end users over time.

Blob prices were historically too cheap, for too long, and didn’t track real-time demand.

The core issue with Ethereum’s initial blob fee design was not a lack of demand, but a failure of price discovery. While blob usage increased steadily, the pricing mechanism proved unable to track utilisation in a stable or consistent way. As a result, blob fees repeatedly collapsed during normal operating conditions.

The chart below highlights two key observations. First, the distribution of daily blob base fees is highly skewed, with the vast majority concentrated at extremely low levels. Second, there is a clear absence of pricing in the middle range: most blobs cost close to zero, a small number were charged very high fees during periods of congestion, and almost none were priced at moderate levels. As a result, blob revenue was highly concentrated: around 90% of cumulative fees were generated on just 12% of days.
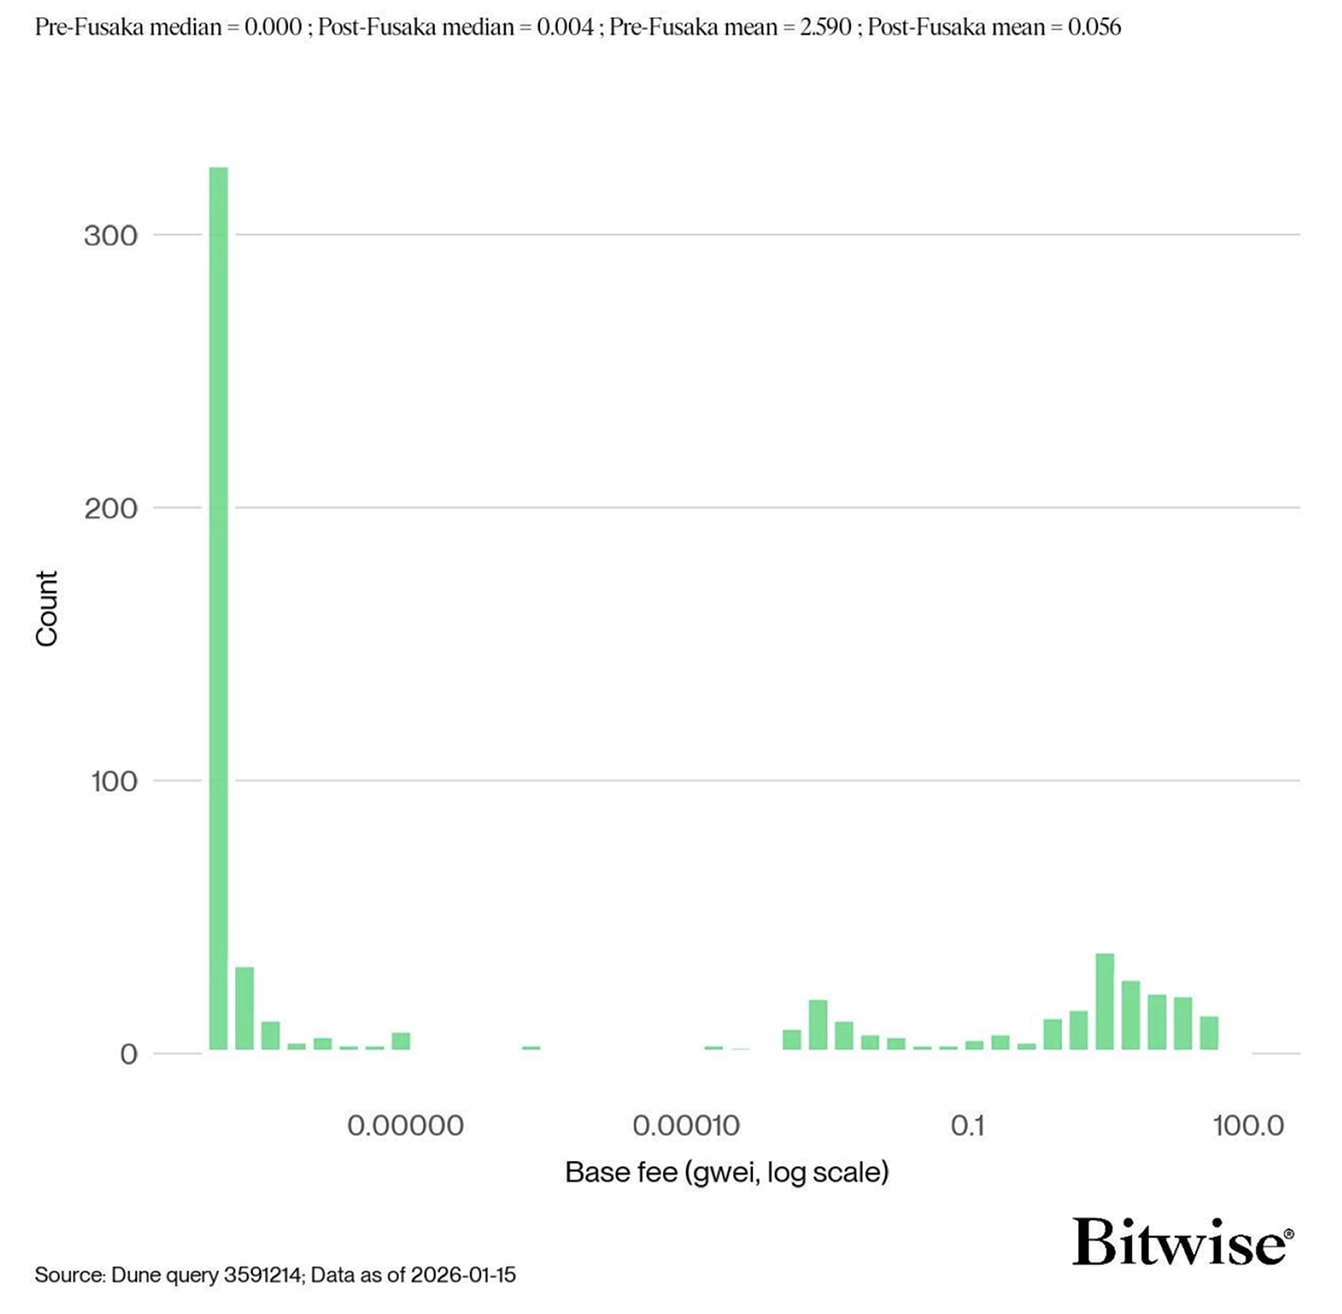
Distribution of daily blob base fee (gwei) image
Source: Dune query 3591214; Data as of 2026-01-15

This is exactly what the time series below illustrates. Blob costs are driven by how many blobs are used per block relative to a target level. When usage reaches this threshold, demand becomes saturated and fees spike sharply, often remaining elevated. Conversely, when utilisation sits persistently below target, excess capacity causes the blob base fee to decay rapidly towards near-zero levels. This dynamic prevents prices from settling in a meaningful middle range and stops the market from stabilising. 
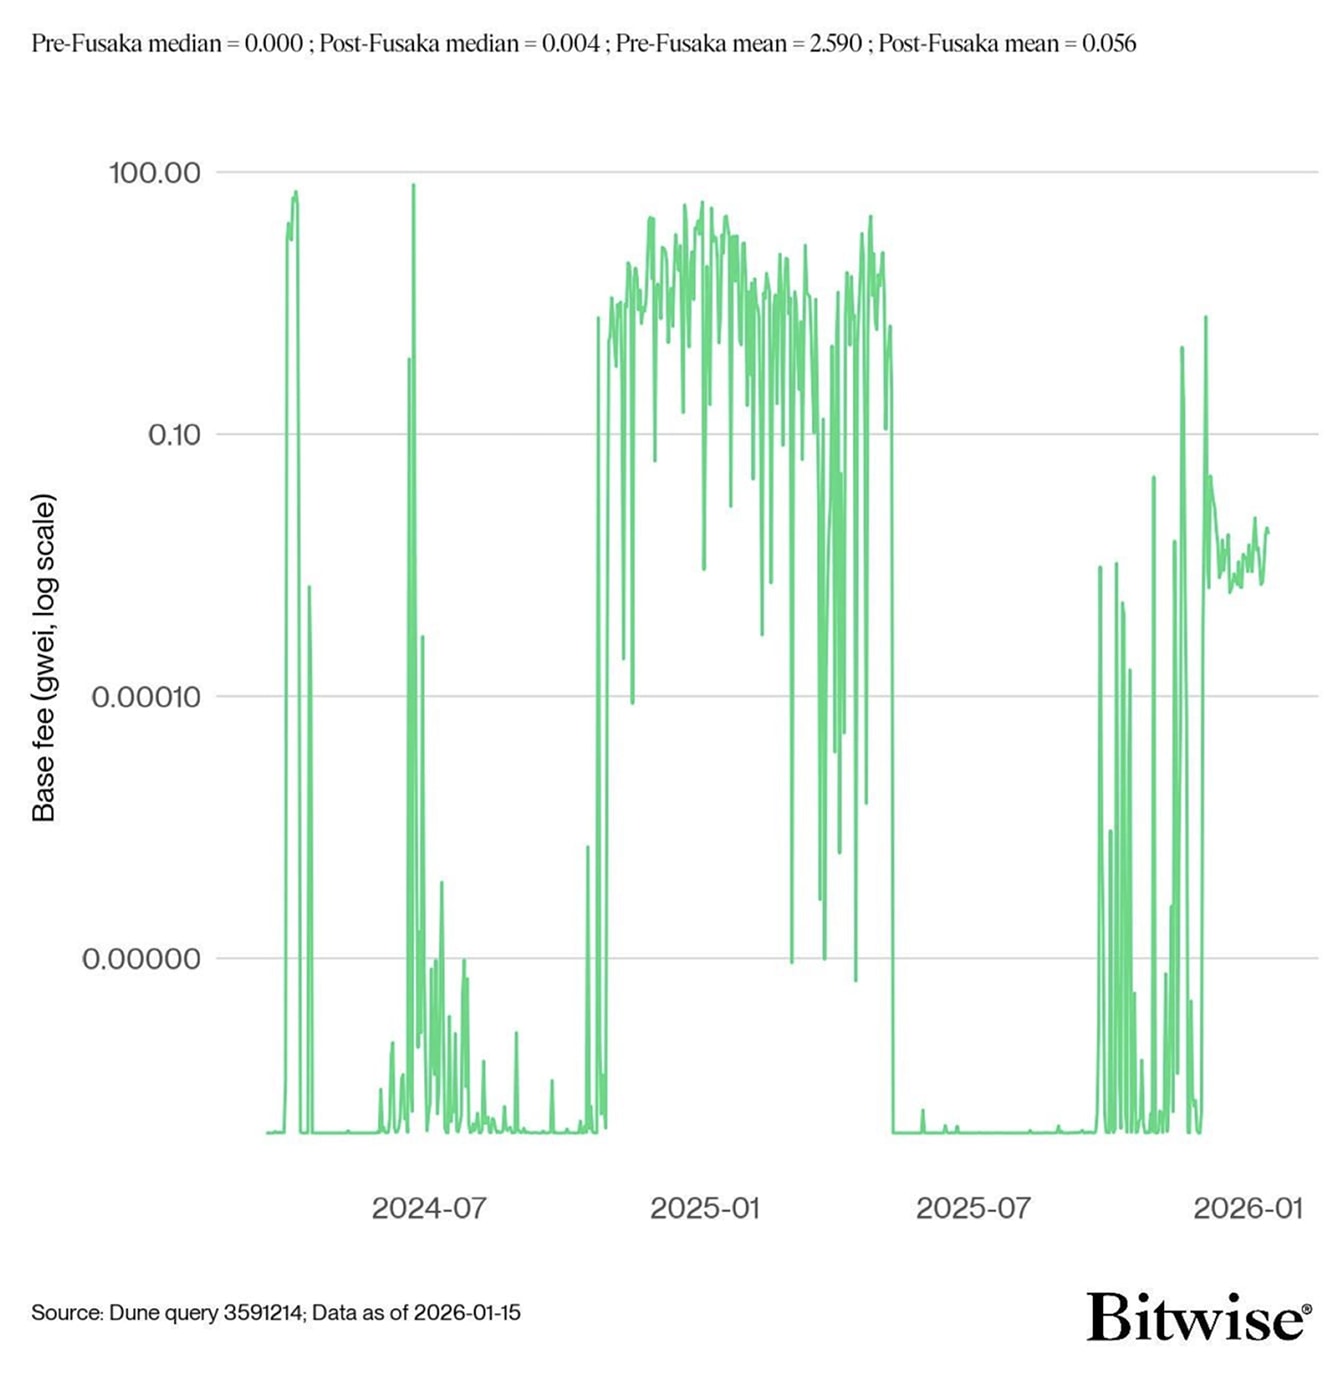
Reported blob base fee (gwei) — query 3591214 image
Dune query 3591214; Data as of 2026-01-15

For sustainable scaling, a blockchain should support moderate, consistent fees, with surge pricing reserved for periods of genuinely extreme demand, rather than oscillating between being almost free and prohibitively expensive.

The post-Fusaka revenue-generation narrative was mostly Fugazi

You might expect creating a floor fee to boost overall Ethereum revenues, but our study shows that the effect will be minimal. Because Ethereum is scaling so effectively, we observe negligible positive effects to Ethereum’s longer-term revenue profile. 

Under different blob pricing regimes, and assuming an ETH price of $3,000, the table translates observed gwei levels into next-twelve-month (NTM) annualised revenue expectations. 

  • Based on post-Fusaka conditions with a median fee of 0.00386 gwei, a mean of 0.056 gwei, and a 75th percentile of 0.00702 gwei, blob fees are projected to generate between 5.39 ETH ($16k) and 78.2 ETH ($234k). 
  • By comparison, using the pre-Fusaka EIP-7918-implied median (0.453 gwei) and mean (3.24 gwei), calculated as if the Fusaka EIP-7918 soft-coupling had been active since the Dencun launch 629 days ago, blob fees would have generated between 632 ETH ($1.8m) and 4,523 ETH ($13.5m). This should be viewed as an upper bound and is skewed by the excessive fee spikes caused by the previously broken blob pricing mechanism.
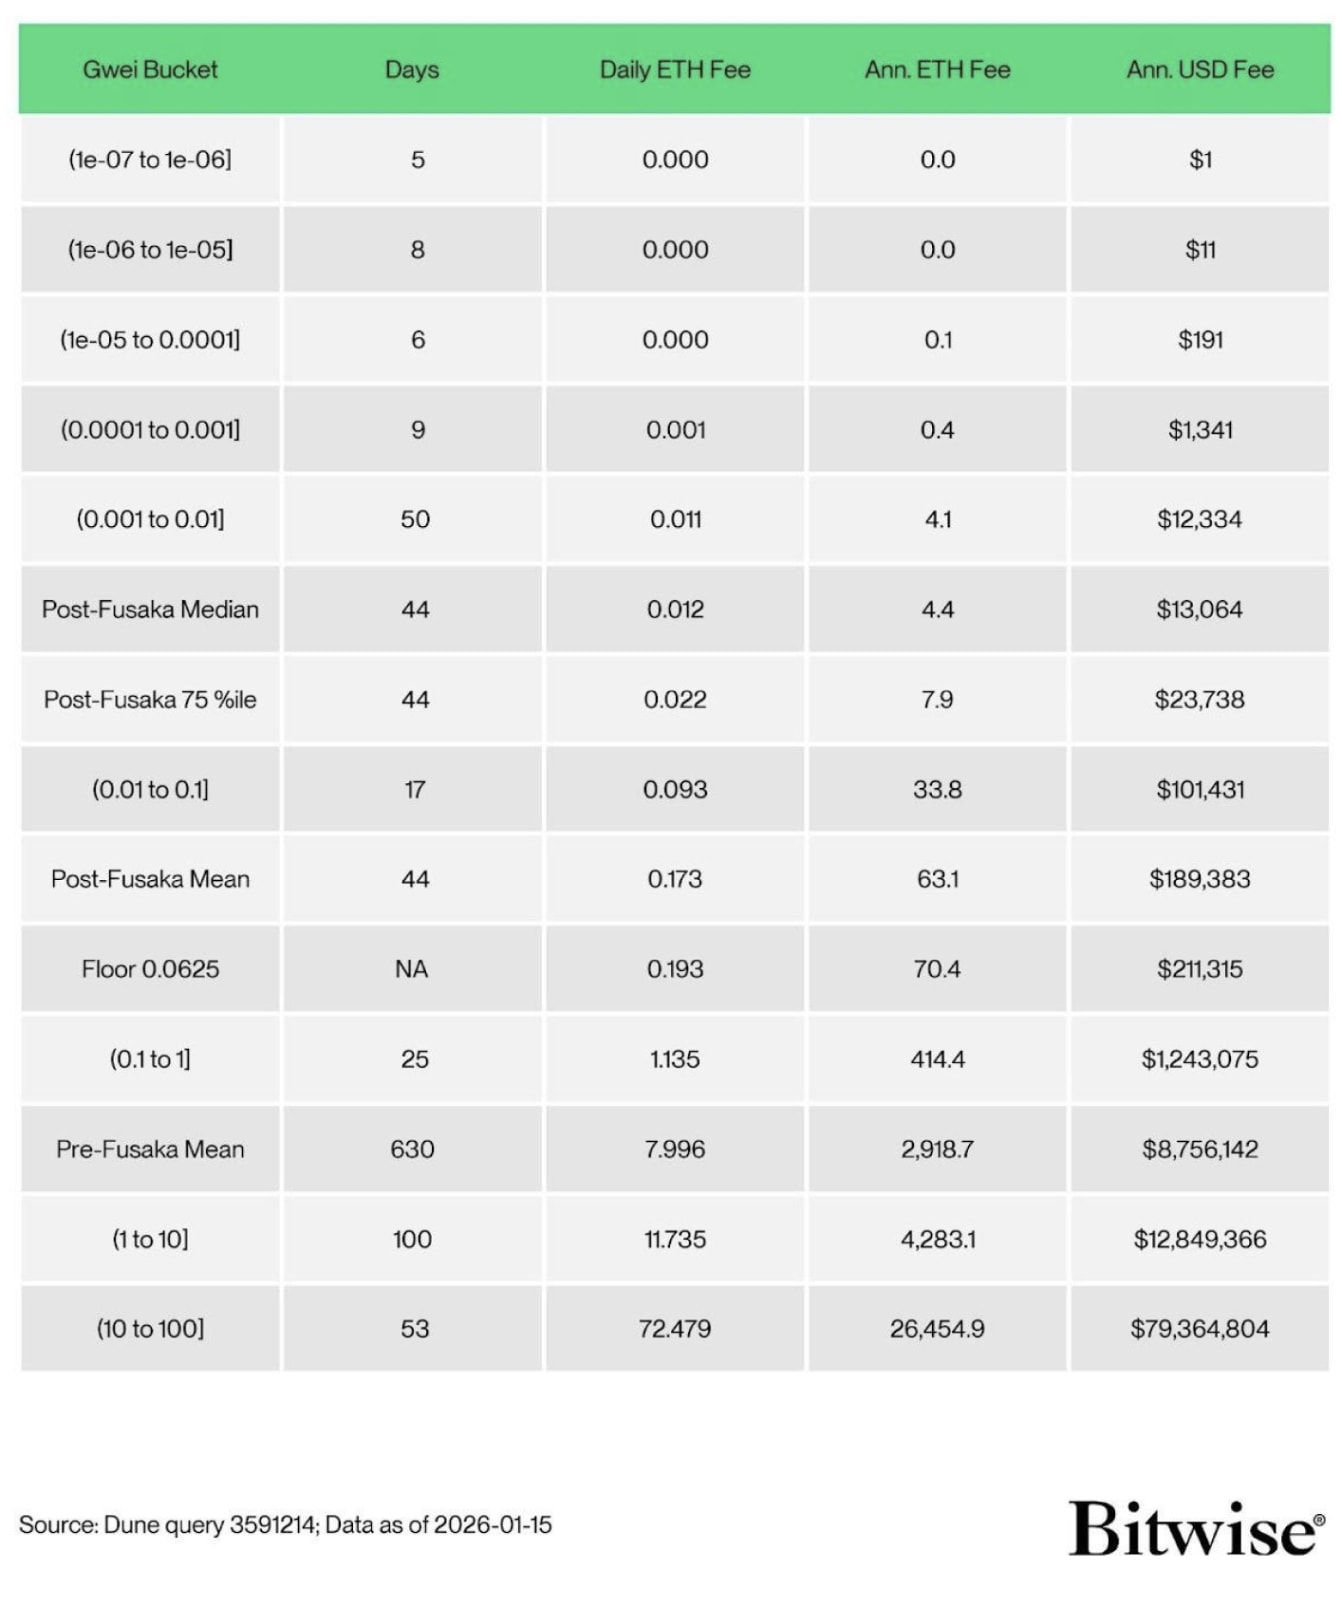
Blob base fee scenarios — query 3591214 image
Source: Dune query 3591214; Data as of 2026-01-15

We view >$1 mn as a realistic upper bound, with post-Fusaka conditions likely to be more representative going forward. Continued scaling across Ethereum and its L2s should drive further increases in the gas limit per block and raise the target number of blobs per block through blob-parameter-only forks. In addition, the Glamsterdam and Hegota upgrades, scheduled for H1 and H2 respectively, should further expand capacity across both Ethereum and the L2 ecosystem.

Conclusion

In the run-up to Fusaka, many argued that EIP-7918 would be game changing for Ethereum. That claim is only partially correct. Instead, the proposal is transformative in terms of user experience for both users and L2s, but not from a revenue-generation perspective.

Prior to Fusaka, blob pricing was fundamentally broken. Supply and demand rarely equilibrated, leading to extreme volatility and mispricing. Fees stayed too low for extended periods, effectively allowing L2s to use Ethereum’s data availability almost for free. When demand did spike, blob fees often became prohibitively expensive for too long, making blobs less competitive than alternative platforms such as Solana. 

The idea that Fusaka would materially boost Ethereum’s revenues was largely based on the assumption that raising the blob fee floor would mechanically lift cumulative fees. In reality, Fusaka primarily fixes the pricing mechanism rather than creating a new revenue engine. By linking blob fees to at least 1/16th of execution fees, it makes pricing more responsive to changes in supply and demand. The key benefit is improved fee predictability, which materially enhances the experience for L2s and end users.

What we have observed so far is telling. While average and median blob fees have increased post-Fusaka, L2 margins have also improved. This apparent contradiction is best explained by greater fee predictability, which allows L2s to optimise their sequencers and price user transactions more efficiently.

Looking ahead, we still expect low annualised blob fees over the next twelve months. Continued scaling will exert downward pressure on prices. Fusaka increased the Layer 1 gas limit, reducing execution fees, and raised the target number of blobs per block, expanding supply faster than demand. With further increases in gas limits and blob capacity likely, the network remains in a structurally low-fee environment.

In short, Fusaka should not be viewed as a revenue-driven inflection point for Ethereum. Its real impact lies in second- and third-order effects: making it more attractive to build and operate Layer 2s, improving margins, and strengthening Ethereum’s role as the settlement layer for scalable on-chain activity.

Bottom Line:

  • Fusaka’s impact is more positive for user experience and L2 margins, than it is on Ethereum’s revenue generation.
  • We expect post-Fusaka blob fees to generate over the next-twelve-months between 5.39 ETH ($16k) and 78.2 ETH ($234k).
  • Over time, blob fees will continue to get cheaper from continued increases in blob counts per block and a continued decline in execution fees.

Important Information

This publication constitutes a marketing communication and is provided for informational purposes only. It does not constitute investment advice, a personal recommendation, or an offer or solicitation to buy or sell any financial instrument.

This document (which may take the form of a presentation, press release, social media post, blog article, broadcast communication or similar instrument – collectively referred to as a “Document”) is issued by Bitwise Europe GmbH (“BEU” or the “Issuer”) and has been prepared in accordance with applicable laws and regulations, including those relating to financial promotions.

Bitwise Europe GmbH, incorporated under the laws of Germany, is the issuer of the Exchange Traded Products (“ETPs”) referenced in this Document under a base prospectus and the applicable final terms, as supplemented from time to time, approved by the German Federal Financial Supervisory Authority (BaFin). The approval of the prospectus by BaFin relates solely to the completeness, coherence and comprehensibility of the prospectus in accordance with the Prospectus Regulation and does not constitute an endorsement, recommendation or assessment of the merits of the products.

The market analyses, views and scenarios presented reflect the assessment as of the date of publication and are based on information considered reliable. However, no representation or warranty is made as to their accuracy or completeness. Forward-looking statements involve risks and uncertainties and are not guarantees of future performance. Past performance is not a reliable indicator of future results.

Capital at risk. Cryptoassets are highly volatile and involve a high degree of risk. The value of investments in cryptoassets and crypto-linked ETPs may fluctuate significantly, and investors may lose part or all of their invested capital. No capital protection or guaranteed compensation mechanism applies in respect of market losses.

Any investment decision should be made solely on the basis of the relevant base prospectus, the applicable final terms and the key information document, in particular the section entitled “Risk Warning”. The base prospectus, final terms and additional risk information are available at: www.bitwiseinvestments.eu

Access to certain documents may require self-certification regarding your jurisdiction and investor status and may be subject to additional disclaimers and important information.

For further details, please refer to the full disclaimer available at: www.bitwiseinvestments.eu/disclaimer

About Bitwise

Bitwise is one of the world’s leading crypto specialist asset managers. Thousands of financial advisors, family offices, and institutional investors across the globe have partnered with us to understand and access the opportunities in crypto. Since 2017, Bitwise has established a track record of excellence managing a broad suite of delta-one, index and active solutions across ETPs, ETFs, separately managed accounts, private funds, and hedge fund strategies, spanning both the U.S. and Europe.

Contact

General Inquiries europe@bitwiseinvestments.com
Institutional investors clients@bitwiseinvestments.com

Related articles you may like

Welcome to Bitwise

Select your location

Welcome to Bitwise

Confirm your location to help us deliver the site experience most relevant to you

Welcome to Bitwise

Confirm your location to help us deliver the site experience most relevant to you

Welcome to Bitwise

Confirm your location to help us deliver the site experience most relevant to you

  • English
  • Deutsch
  • Italiano
  • Français
  • Svenska
Country
  • English
  • Deutsch
  • Italiano
  • Français
  • Svenska
Country
Important Notice:
The distribution of the information and material on this website may be restricted by law in certain countries. None of the information is directed at, or is intended for distribution to, or use by, any person or entity in any jurisdiction (by virtue of nationality, place of residence, domicile or registered office) where publication, distribution or use of such information would be contrary to local law or regulation.
Important Notice:
You are about to access the Bitwise Asset Management website. Based on your location, clicking 'Proceed to US website' below will redirect you to the US-specific website.
Important Information – Please Read Before Proceeding

This website is operated by Bitwise Europe GmbH (“Bitwise”, “we”, “us”). The information on this website is intended for UK retail clients and other visitors in the United Kingdom. If you are not in the UK, local laws and rules may differ and the materials here may not be appropriate for you.

All content is provided for general information only. It does not constitute investment advice, tax or legal advice, an offer, or a solicitation to buy or sell any investment and must not be relied upon to make an investment decision. You should consider whether an investment is suitable for your circumstances and, where appropriate, seek independent professional advice.

Cryptoassets and crypto-linked products are high-risk. The FCA categorises retail crypto promotions as Restricted Mass Market Investments (RMMI). As such, additional prominence, risk-warning and risk-summary requirements apply to retail communications. You could lose all the money you invest.

Investments in cryptoassets or many crypto-linked products are generally not covered by the UK Financial Services Compensation Scheme (FSCS) or the Financial Ombudsman Service (FOS). You should not expect to be protected if something goes wrong.

Access to certain pages, features, or transactions may be subject to client categorisation and appropriateness assessments required by FCA rules. We may ask you to complete checks or declarations before you can proceed.

Where this website contains a retail financial promotion for crypto or other RMMIs, you will see the FCA-prescribed risk warning and a link (“Take 2 mins to learn more”) to the FCA risk summary presented in a pop-up or dedicated page. For convenience, you can access that summary here at any time.

Where performance is shown, past performance is not a reliable indicator of future results. Any projections, targets, or forward-looking statements are inherently uncertain and may not be realised. Fees and expenses reduce returns.

Returns may be reduced by fees, charges, spreads, and taxes. Tax treatment depends on individual circumstances and may change. Seek professional advice if unsure.

Where a prospectus (including any base or supplemental prospectus) or KID/PRIIPs KIID or equivalent is provided, it is regulatory disclosure, not marketing. Those documents are generally outside the UK financial-promotion restriction.

In line with FCA rules for high-risk investments, we do not offer incentives to invest (e.g., refer-a-friend bonuses, monetary/non-monetary perks) in relation to retail crypto promotions.

External links are provided for convenience only. We do not control and are not responsible for third-party websites or their content. We take reasonable care to ensure accuracy but do not guarantee completeness, timeliness, or availability of the website or its contents; information may change without notice.

Our products or services may not be available in all jurisdictions or to all investors. Access may be restricted by law. You are responsible for understanding and complying with applicable laws and regulations.

For queries or complaints, contact: clients@bitwiseinvestments.com | Additional contact and legal information is available in our Terms of Website Use and Privacy Notice.

Copyright & trademarks © 2025 Bitwise. All rights reserved. Product names, logos and brands are property of their respective owners

Avis Important

Les produits d’investissement domiciliés en Europe et présentés sur ce site sont des Exchange Traded Commodities (« ETC »), instruments financiers considérés comme des titres de créances complexes par l'Autorité des Marchés Financiers, présentant des risques difficilement compréhensibles par le grand public. À ce titre, leur distribution en France répond à des règles spécifiques. Il relève de la responsabilité des intermédiaires et investisseurs professionnels souhaitant offrir des ETCs à leurs clients de s'assurer que leur distribution auxdits clients est réalisée dans le respect de la réglementation française.

Important Information

The information provided in this advertising material is for informative purposes only and does not constitute investment advice, a recommendation or solicitation to conclude a transaction.

This website and all documentation and other information provided on or via it (all together this “website”) is issued by Bitwise Europe GmbH (“BEU” or the “Issuer”). This website is provided for illustrative, educational and information purposes only and may be subject to change.

Where this website constitutes an advertisement within the meaning of Article 22 of Regulation (EU) 2017/1129, as amended (the “Prospectus Regulation”) or Regulation 3 of the Public Offers and Admissions to Trading Regulations 2024, and the relevant offer or admission to trading is subject to an obligation to draw up a prospectus, the applicable prospectus has been or will be published and is or will be available in the Resources section of the Bitwise Europe website at bitwiseinvestments.eu/resources/.

Bitwise Europe GmbH, Thurn- und Taxis-Platz 6, 60313 Frankfurt am Main, Germany, registered with the commercial register of the local court of Frankfurt am Main under HRB 116604, is the issuer of Exchange Traded Products (“ETPs”) described in this website under an applicable base prospectus approved by BaFin, or, where applicable, another competent authority, as supplemented from time to time, and the applicable final terms. Final terms are published and filed with the relevant competent authority in accordance with applicable law and are not subject to approval. The relevant product documentation identifies the competent authority that approved the applicable prospectus.

Approval of a prospectus means that the competent authority has scrutinised it against the applicable standards of completeness, comprehensibility and consistency, and it does not constitute an endorsement or recommendation of the Issuer or the ETPs. If you are considering investing in products issued by BEU you should check with your broker or bank that such products are available in your jurisdiction and suitable for your investment profile. A decision to invest any amount in an ETP offered by BEU should take into consideration your specific circumstances after seeking independent investment, tax and legal advice.

You should read the relevant base prospectus, any supplements and the applicable final terms before investing and, in particular, the section entitled “Risk Factors” for further details of the risks associated with an investment. Where required, you should also read the key information document under Regulation (EU) No 1286/2014 (PRIIPs), the product summary under the Consumer Composite Investments (Designated Activities) Regulations 2024 or the equivalent product disclosure applicable in your jurisdiction. The prospectuses, supplements, final terms, key information documents and other regulatory documents relevant to BEU’s ETPs are available electronically and free of charge in the “Resources” section of the Bitwise Europe website at bitwiseinvestments.eu/resources/.

Access to those documents is not conditional on completion of a registration process, on any country or investor-type selection, on acceptance of the Terms of Website Use or of any disclaimer limiting legal liability, or on payment of a fee, in accordance with Article 21(4) of the Prospectus Regulation or the FCA Handbook, Prospectus Rules. Warnings specifying the jurisdictions in which an offer or an admission to trading is being made may be displayed in connection with certain content and are not disclaimers limiting legal liability.

Any country or investor-type selection used on this website determines which marketing content may be displayed. It does not itself constitute a formal regulatory client classification, an assessment of appropriateness or suitability, confirmation of legal eligibility to invest, or investment advice.

If You Are in the UK, US, or Canada

Information contained in this website does not constitute, and under no circumstances is to be construed as, an offer to sell or a solicitation of an offer to buy securities, or any other step in furtherance of a public offering, in the United States or Canada, or any state, province or territory thereof, where neither the Issuer nor its products are authorised or registered for distribution or sale and where no prospectus of the Issuer has been filed with any securities regulator. Neither this website nor information in it should be taken, transmitted or distributed (directly or indirectly) into the United States.

In the UK, this website is provided for information purposes only, and is in any event provided in accordance with the exemption to the requirement, set out under section 21 of the Financial Services and Markets Act 2000, that communications relating to invitations or inducements to engage in investment activity be approved by a person authorized by the Financial Conduct Authority. As such, this website is directed only at persons who fall within a relevant exemption to the restriction on financial promotions as set out in the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005, such as: investment professionals (Article 19); high net worth individuals (being individuals who have an annual income of at least £100,000 and / or net assets of at least £250,000) (Article 48); high net worth companies, unincorporated associations etc. (Article 49); sophisticated investors (being individuals with a current appropriate certificate stating that they are sufficiently knowledgeable to understand the risks associated with this investment) (Article 50); self-certified sophisticated investors (being individuals who have: worked in the past two years in a professional capacity in the private equity sector or in the provision of finance for small and medium enterprises; been a director of a company turning over at least £1 million annually in the last two years; made two or more investments in an unlisted company in the last two years; or been a member of a network or syndicate of business angels for more than six months) (Article 50A); and associations of high net worth or sophisticated investors (Article 51).

Persons who do not fall within a relevant exemption should not access, or otherwise rely or act on this website, rather they should instead proceed to the Private Investor version of the website. By accessing this website, you confirm that you fall within a relevant exemption.  Neither the Issuer nor its products are authorised or regulated by the UK Financial Conduct Authority, and the content of this promotion has not been approved by an authorised person within the meaning of the Financial Services and Markets Act 2000. Reliance on this promotion for the purpose of engaging in any investment activity may expose an individual to a significant risk of losing all of the property or other assets invested. For further information or any other enquiry regarding the matters to which this website relates, you may contact us at eu-legal@bitwiseinvestments.com.

Publications & Social Media Disclosure

Social media communications, including posts on LinkedIn and X, (all together “Social Media”) may constitute advertisements, financial promotions, investment recommendations within the meaning of Regulation (EU) No 596/2014, the Financial Services and Markets Act 2000 or other regulated communications depending on their content and the jurisdiction in which they are communicated. Unless expressly stated otherwise, they are not intended to constitute investment advice or a personal recommendation.

BEU makes all reasonable efforts to ensure that the information contained in documents and on Social Media is accurate and reliable; however, errors may occur. To the extent permitted by applicable law, documents and materials available on Social Media are provided without any express or implied warranties as to accuracy, validity, timeliness or completeness. Nothing in this paragraph excludes or limits any statutory or regulatory responsibility or liability that cannot lawfully be excluded or limited, including obligations applicable to advertisements or financial promotions and liability relating to a prospectus or other regulatory disclosure.

Unless expressly endorsed or adopted by Bitwise Europe, comments expressed by members of the online community represent those persons’ own views and are not endorsed by Bitwise Europe.

Risks of ETPs & Cryptocurrencies

An investment in an ETP backed by one or more cryptocurrencies, such as those issued by BEU, is dependent on the performance of the underlying cryptocurrency, less costs, but it is not expected to match the performance of the underlying asset precisely. Investing in ETPs also involves numerous risks including general market risks relating to underlying, adverse price movements, currency, liquidity, operational, legal and regulatory risks and investors should be prepared to lose some or all of the amount invested.

ETPs backed by cryptocurrencies are highly volatile assets and performance is unpredictable. Past performance is not a reliable indicator of future performance. The market price of ETPs will vary and they do not offer a fixed income. The value of any ETP may be affected by exchange rates and the price movement of its underlying cryptocurrency(ies). This website may contain forward looking statements including statements regarding Bitwise Europe’s belief or current expectations with regards to the performance of certain asset classes. Forward looking statements are subject to certain risks, uncertainties and assumptions, and there can be no assurance that such statements will be accurate and actual results could differ materially from those indicated. You must not place reliance on forward-looking statements or any other similar information contained in this website.

Cryptocurrencies are highly volatile and are known for their extreme and rapid fluctuations in prices. While there may be potential for significant gains, you are at risk of losing part or all of your entire capital invested. The price of cryptocurrencies can fluctuate widely and, for example, may be impacted by global and regional political, economic or financial events, regulatory events or statements by regulators, investment trading, hedging or other activities by a wide range of market participants, forks in underlying protocols, disruptions to the infrastructure or means by which crypto assets are produced, distributed, stored and traded. Characteristics of cryptocurrencies and divergence of applicable regulatory standards create the potential for market abuse. The price of cryptocurrencies may also change due to shifting investor confidence in future outlook of the asset class.

For a detailed overview of risks associated with cryptocurrencies and specifically associated with BEU’s products, please refer to the prospectus and final terms, which are available in the “Resources” section of the Bitwise Europe website at bitwiseinvestments.eu/resources/. You should only invest if you are capable of understanding and evaluating the risks involved. If you are in doubt as to whether an investment is appropriate for you, you should consult an authorised person who specialises in advising on investments including crypto-backed ETPs.

Avis Important

Les produits présentés sur ce site internet ne sont ni destinés à être distribués, ni accessibles aux investisseurs non-professionnels résidant en France. Toute information figurant sur ce site est fournie à titre informatif uniquement. Pour toute information complémentaire, veuillez contacter votre conseiller financier ou votre intermédiaire habituel.